We collect cookies to enhance your browsing experience.Learn more
Global Polysilicon Market Size is valued at USD 17.08 Bn in 2025 and is predicted to reach USD 53.03 Bn by the year 2035 at an 12.2% CAGR during the forecast period for 2026 to 2035.
Polysilicon Market Size, Share & Trends Analysis Distribution by Production Process (Siemens (TCS-CVD), Fluidized Bed Reactor (Silane-FBR), Upgraded Metallurgical-Grade (UMG)), by End-User Industry (Solar Photovoltaics, Electronics and Semiconductors) and Segment Forecasts, 2026 to 2035.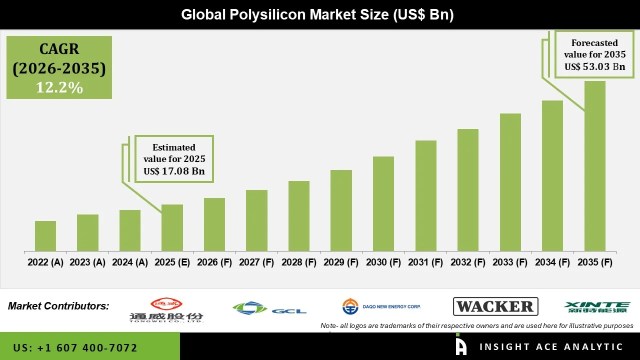
Polysilicon is becoming an increasingly important material in the global renewable energy and semiconductor industries, driven largely by the continued expansion of solar photovoltaic (PV) installations and rising demand for advanced electronic devices. Polysilicon is a highly purified form of silicon that serves as a key raw material for manufacturing solar cells, wafers, and semiconductor components. As countries increase investments in renewable energy, expand solar power capacity, and strengthen domestic semiconductor manufacturing, demand for high-purity polysilicon is continuing to grow. The material plays an important role in supporting the global transition toward cleaner energy while also meeting the requirements of the rapidly expanding electronics industry.
The solar photovoltaic industry is a key reason for the rising demand for polysilicon. More utility-scale solar farms, rooftop systems, and distributed solar projects are being installed, which keeps demand for solar-grade polysilicon steady. Government incentives, renewable energy goals, lower solar technology costs, and the push to use less fossil fuel are all driving new investments in solar power. At the same time, better solar cell technology means high-quality, pure polysilicon is more
important than ever. Manufacturers are increasing production and improving their processes to keep up with the needs of the solar PV supply chain.
Technological developments are further influencing the polysilicon market. Manufacturers are adopting advanced production technologies such as the Siemens process and fluidised bed reactor (FBR) technology to improve production efficiency, purity, and cost competitiveness. The Siemens process remains widely used to produce high-purity polysilicon, while FBR technology offers potential advantages in continuous production and energy efficiency. Upgraded metallurgical-grade (UMG) silicon also represents an alternative production approach for specific applications. Ongoing improvements in purification, energy consumption, production yields, and manufacturing processes are helping producers meet changing requirements from solar and semiconductor customers.
Developments across the global solar and semiconductor supply chains also influence the polysilicon market. Manufacturers are increasing production capacity, entering long-term supply agreements, improving manufacturing efficiency, and investing in new facilities to strengthen their market position. Major producers are also focusing on reducing production costs and improving energy efficiency because polysilicon manufacturing can be energy-intensive. Access to reliable and competitively priced electricity is therefore an important consideration for producers when selecting production locations and expanding capacity. Even with these opportunities, the polysilicon industry faces some challenges. Price swings, supply and demand imbalances, high energy needs, raw material shortages, and changes in production capacity can all impact the market. The industry is also affected by shifts in trade policies, tariffs, government rules, and supply chain disruptions.
Environmental issues are becoming more important for polysilicon makers. Because producing polysilicon uses a lot of electricity, companies are looking for ways to cut energy use and lower carbon emissions. Using renewable energy, making production more efficient, and investing in cleaner technologies can help reduce the environmental impact. These steps matter more now as solar manufacturers and customers pay closer attention to the carbon footprint and sustainability of their supply chains.
The global polysilicon market is growing mainly because more people are using solar photovoltaic (PV) technology and the semiconductor industry is expanding. Polysilicon is essential for making solar cells and semiconductor wafers, so its demand rises with advances in renewable energy and electronics. Many governments are investing more in solar power and setting renewable energy goals to rely less on traditional energy sources. As more solar farms, rooftop systems, and distributed solar projects are built, the need for solar-grade polysilicon continues to increase. Investments in semiconductor manufacturing are also boosting demand for high-purity polysilicon. As artificial intelligence, data centers, electric vehicles, consumer electronics, and advanced computing grow, the need for semiconductor components increases. Manufacturers are building new facilities and expanding current ones to keep up. As both the solar and semiconductor industries grow, the demand for high-quality polysilicon is expected to keep rising, helping the market expand overall.
The polysilicon industry faces challenges that can slow market growth, especially high energy use and price swings. Making polysilicon, especially with traditional methods, uses a lot of electricity. When electricity prices change, production costs and profits are affected. To manage these issues and lower environmental impact, manufacturers are working to use energy more efficiently and switch to renewable energy sources. Polysilicon prices can change based on demand for solar modules, how much is produced, inventory, and overall supply and demand. If manufacturing grows too quickly, there can be too much supply, which lowers prices. On the other hand, supply problems can push prices up. Since much of the production is in a few countries, there are supply-chain risks for solar and semiconductor companies. Trade rules, tariffs, and political changes can also affect global supply chains. To manage these risks, manufacturers are improving efficiency, diversifying supply chains, signing long-term contracts, and investing in production facilities in different locations.
The solar photovoltaics segment is expected to account for a significant share of the global polysilicon market due to the continued expansion of solar power generation worldwide. Polysilicon is an essential raw material for producing crystalline silicon solar cells and wafers, so demand for the material is closely tied to solar PV installations. The growing deployment of utility-scale solar projects, rooftop systems, and distributed solar generation is driving strong demand for solar-grade polysilicon. Governments and energy companies are investing in renewable energy projects to increase clean electricity generation and reduce carbon emissions. Falling solar technology costs and improvements in solar cell efficiency are also encouraging wider adoption of photovoltaic systems. In addition, manufacturers across the solar value chain are expanding production capacity to meet growing global demand. These developments are expected to support continued demand for polysilicon from solar manufacturers and maintain the solar PV industry’s important role in the overall market.
The electronics and semiconductor segment is expected to grow quickly as more advanced electronic devices and semiconductor parts are needed. High-purity polysilicon is essential for making semiconductor wafers, which are used in integrated circuits and many electronic products. Fast growth in artificial intelligence, cloud computing, data centers, electric vehicles, smartphones, and advanced computing is driving up global demand for semiconductors. Governments and big tech companies are investing in local semiconductor manufacturing to make supply chains stronger and rely less on foreign production. New factories and wafer plants will likely increase demand for high-purity polysilicon. As semiconductor technology improves and more electronic uses appear, the need for high-quality silicon materials should keep growing, giving polysilicon producers more opportunities.
Asia Pacific represents a leading region in the global polysilicon market, supported by its large solar manufacturing base, expanding renewable energy capacity, established semiconductor supply chain, and significant polysilicon production capabilities. China plays a particularly important role in the regional market due to its extensive presence across the solar photovoltaic value chain, including polysilicon, wafers, solar cells, and modules. 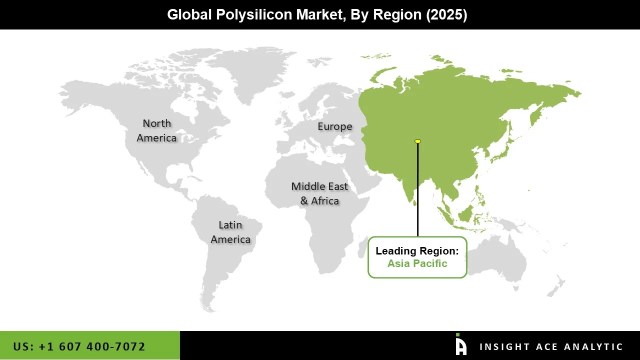
The region also includes major manufacturing and technology markets such as India, Japan, and South Korea. The rapid development of solar power projects across Asia Pacific is generating substantial demand for solar-grade polysilicon. China continues to expand renewable energy capacity, while India is increasing investments in domestic solar manufacturing and clean energy infrastructure. Japan and South Korea also have established electronics and semiconductor industries that contribute to regional demand for high-purity silicon materials. Asia Pacific’s strong manufacturing base, robust production infrastructure, rising renewable energy investment, and many major polysilicon producers help maintain the region’s leading market position.
• In May 2026, GCL Technology Holdings announced a comprehensive strategic transformation from a granular-silicon-focused business toward a global multi-product new energy materials platform. The company plans to build on its FBR granular silicon capabilities while expanding into silicon-, lithium-, and carbon-based materials, supporting diversification and longer-term growth.
• In March 2026, Tongwei also continued advancing next-generation photovoltaic technologies, including perovskite-silicon tandem cells. The company reported progress toward commercial-scale tandem cell and module development, indicating continued investment beyond conventional crystalline-silicon PV technologies.
This study employed a multi-step, mixed-method research approach that integrates:
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Secondary data for the market study was gathered from multiple credible sources, including:
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Primary interviews for this study involved:
Interviews were conducted via:
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
This ensured that the dataset used for modelling was clean, robust, and reliable.
The bottom-up approach involved aggregating segment-level data, such as:
This method was primarily used when detailed micro-level market data were available.
The top-down approach used macro-level indicators:
This approach was used for segments where granular data were limited or inconsistent.
To ensure accuracy, a triangulated hybrid model was used. This included:
This multi-angle validation yielded the final market size.
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Given inherent uncertainties, three scenarios were constructed:
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Polysilicon Market Size is valued at USD 17.08 Bn in 2025 and is predicted to reach USD 53.03 Bn by the year 2035
The Polysilicon Market is expected to grow at a 12.2% CAGR during the forecast period for 2026 to 2035
Tongwei Co. Ltd., GCL Technology Holdings, Daqo New Energy Corp., Wacker Chemie AG, Xinte Energy Co. Ltd., East Hope Group, OCI Company Ltd., Hemlock Semiconductor, REC Silicon ASA, Asia Silicon (Qinghai) Co. Ltd. and Others.
Polysilicon Market is segmented into Production Process, End Use Industry and Other.
Asia Pacific region is leading the Polysilicon Market.
Determine the appropriate license for your report
Our qualitative and quantitative market intelligence solutions help businesses expand through actionable market and competitive intelligence.
North America: +1 607 400-7072
© 2026 InsightAce Analytic Pvt. Ltd. All rights reserved.
| Terms & Conditions
| Privacy Policy
| Disclaimer
| Return Policy
| FAQ
See the data, methodology, and competitive landscape preview & delivered to your inbox shortly.
Trusted by Sartorius, L’Oreal, Fujifilm & 370+ organizations
Links
WebSite
Follow Now.Solar via Email
Join 4,388 other subscribersSolar Now
Top Posts & Pages
- Register by Aug. 1 for free solar photovoltaic level one certification course - Athens County Independent
- Clearway secures financing, starts construction on 650MW Missouri solar project - PV Tech
- Tesla’s full EV lineup can now also provide home backup energy - Solar Power World
- The Museum of Flight to Begin Installation of Nearly 2,000 Solar Panels on Aviation Pavilion - Vintage Aviation News
- AI-Guided Room-Temperature Synthesis Scales Perovskite Nanocrystals For 19% Efficient Solar Cells - AZoNano
- A New Crop of Solar Panels Is the U.S.’s Best Hope of Catching China - The New York Times
- Canada signs on to pledge to fight subsidized overproduction of EVs, batteries, and solar panels - The Globe and Mail
- Bondada Engineering Wins INR 11.54 Billion EPC Order for 270MWp Solar Project in Maharashtra - IndexBox
-
New Posts
- Gujarat's Gopin Group New Entrant In India's ALMM-II (Solar Cells) – Saur Energy
- Smart Gunes Enerjisi Secures $19.5 Million Solar Panel Contract with Arçelik – The Globe and Mail
- Greece is turning a former coal mine into a giant renewable-energy battery; the Kardia project will use t – The Times of India
- Infinity Power and AIKO expand African solar partnership – Africa Business Communities
- Polysilicon Market Size, Share, Trend, Revenue Report 2026 to 2035 – Insightace Analytic
- Solex Energy Secures Rs. 1.94 bn in TOPCon Module Orders – Construction World
- Mova Tech launches 4 kWh residential battery with AI-based energy management – pv magazine Global
- Texas Powerwall owner gets recall notice, then Sunrun partner bills $450 to 'troubleshoot' – The Cool Down
- US solar industry to reflect on optimistic policy landscape at PV CellTech 2026 – PV Tech
- Plans for a solar panel recycling plant in Tartu – ERR
Calendar
Archives
Categories
Meta
Tags
- "Bharat Heavy Electricals Limited (BHEL)"
- "Maharishi Solar Technology"
- "Premier Solar Systems (P) Ltd."
- "Renew Solar Power Ltd. (Consortium with
- "Sharda Construction & Corporation Pvt.
- "UPV Solar - Udhaya Energy Photovoltaics Pvt Ltd"
- "USL Photovoltaics PVT Ltd."
- "Websol Energy System Limited"
- "West Bangal Power Development Corp.
- "West Bangal State Electricity Distribution
- $1 billion
- $541 million
- <!-- wp:paragraph --> <p>India has made substantial progress in domestic solar module manufacturing capacity in recent years. However
- vertically integrated domestic solar manufacturing ecosystem.Without large-scale domestic manufacturing of upstream PV value chain products
- -Rural
- 1 GW
- 1 GW Solar PV
- 1 MW
- 1 MW to 5 MW
- 1 nanometer
- 1/SPP-57/2012/751
- 2.44
- 2.97 per kilowatt-hour (kWh)
- 4G Identity Solution Pvt. Ltd.
- 5MW
- 7.5GW
- 8minutes Future Energy Pvt. Ltd.
- 13 GW in India
- 21" Century Enviro Engineers Pvt Ltd
- 40 MW
- 40GW Solar Rooftops
- 80IA
- 80IA Tax Benefit
- 80MW
- 100GW Solar
- 130MW Karnataka Solar RfS
- 300 GW India
- 400 MW Solar PV Projects
- 400 PPM
- 500 crore (US$2.5 billion) for solar module manufacturing. The Indian government’s ambitious targets and support for the solar sector have made indigenous PV manufacturi
- 500 kWp
- 600 MW solar power projects to be inaugurated in Gujarat on 19th April 2012 Solar
- 1000MW Solar Tamil Nadu
- 2000MW
- 2000MW Solar
- 2011
- 2012
- 2014)
- 2015
- 2016-17
- 2016.
- 2017
- 2021
- 2030
- 2050
- a-Si
- Aadi Technologies Pvt Ltd
- Abengoa Solar
- Abhishek Enterprises
- Ablers Services Private Limited
- abolishing
- Abound Solar
- Abu Dhabi
- abundant energy source
- Accelerated Depreciation
- Accelerated Depreciation benefit
- Access Solar
- Acciona
- ACME
- ACME Bikaner Solar
- Acme Clean Tech Solutions Ltd
- Acme Gurgaon Power Pvt Ltd
- ACME Jaipur Solar Power Private Limited
- Acme Mumbai Power Pvt Ltd
- Acme Rajdhani Power Pvt Ltd
- Acme Solar
- Acme Solar (510 MW of bids)
- Acme Solar-Gurgaon
- ACME SOLAR HOLDINGS PRIVATE LIMITED
- Acme Solar Holdings Pvt Ltd
- ACME Tele Power
- AC module
- ACoS
- ACP
- Acva Solar Vadodra
- ACWA
- Adams
- Adani
- AdaniEnterprises Ltd
- Adani Power
- Adani Power (492 MW)
- Aditi Solar Hyderabad
- Aditya Birla
- aditya birla group
- Aditya Birla Renewables Ltd
- Aditya Green Energy Pvt Ltd
- Aditya Green Energy Pvt Ltd Latur
- Aditya Green Latur
- Aditya Housing ft Infrastructure Development Corporation Pvt Ltd
- Aditya Medisales Ltd
- Aditya Thermal Energy Private Limited
- Aditya ThermalEnergy Pvt Ltd
- adoption subsidies
- Ados Renewable Private Limited
- ADS Projects New Delhi
- Advanced Battery Technologies
- advanced industrial science
- Advanced Industrial Science and Technology
- advantages of solar energy
- advisory
- Advit Ventures Private Limited
- Aero-Genrators/Hybrid systems
- AES
- Affidavit
- Africa
- African
- agency icra
- Aggregate Revenue Requirement
- Agni Power Kolkata
- Agra
- agri-food
- Agricultural manures based power generation projects
- Agriculture and Rural Development
- Agriculture Pumps
- Agriculture Solar
- Agrivoltaics
- agro-residues
- Ahluwalia
- Ahmedabad
- Air
- Air cleaning paints
- Air Mass
- Air pollution
- air quality
- AIST
- Ajay Prakash Shrivastava
- Ajit Solar
- Ajmer Vidyut Vitran Nigam
- A K Balyan
- AkhileshYadav
- ALEO Manali Hydropower PVt. Ltd.
- Aleo Solar
- Alex Green Energy
- Alex Solar
- Alfa Infra Corp
- Alfa Infraprop Private Limited
- Alien Energy Private Limited
- All India Power Generation
- Almería
- Alpex
- Alpha Infra
- alternative energy sources
- Amaravathi Textiles Pvt Ltd
- Ambica Agarbathies Aroma & Industries Ltd.
- Ambuja
- Ambuja Cement Ltd.
- Amit Kumar
- Amit Patel
- ammonia
- Amogeo Ites India Limited
- Amonix
- Amplus Energy Solutions Pvt Ltd
- amp power company
- Amrit Engineering
- Anand Kumar
- Anand Mahindra
- Ananthapuramu Solar Park
- Ancient Greece
- Andalusia
- Andaman
- Andaman & Nicobar
- Andaman & Nicobar Islands
- Andaman and Nicobar Islands
- and back contact degradation
- Andhra
- Andhra Pradesh
- Andhra Pradesh (Govt. of Andhra Pradesh & APERC)
- Andhra Pradesh Electricity Regulatory Commission
- andhra pradesh government
- Andhra Pradesh Solar
- Andhra Pradesh Solar Policy
- andhra pradesh state
- Andrew Witkin
- Andromeda
- André Borschberg
- and the Confederation of Indian Industry
- and wind energy in the first week of December
- Angela Merkel
- Angle of Incidence
- Anil Agarwal
- Anil Ambani
- Anil Jain
- Anil Kakodkar
- annual growth
- Antarctic
- anti-dumping
- anti-dumping duty
- anti-dumping investigation
- antidumping directorate
- antidumping duty
- AP
- AP 1000MW Solar plant
- apartment residents
- APEDA
- APERC
- AP Genco
- APNPDCL
- a power price hike in China and a surge in international freight charges have inflated module prices in 2021 by more than 25% . This highlights the need for a sustainable
- APPC
- appellate tribunal
- Appellate Tribunal for Electricity
- Apple
- Applicable Tariff
- Applied Physics Letters
- approve
- April 2013
- APS
- AP Solar
- AP Solar Bids
- AP Solar Policy
- AP Solar Policy 2012
- APTEL
- APTRANSCO
- AP Transco
- AP under JNNSM Ph-II
- Aradhana Investments Ltd
- Areva
- Argentina
- Arid (cold) and Continental (warm summer) – were studied using a model that in addition to legacy infrastructure optimises investments in wind
- arid desert
- Arizona
- Arjun Green Power
- Army
- ARR
- Artheon Electronics Pvt Ltd
- Arunabha Ghosh
- Arunachal Pradesh
- Arun Mehta
- Aryavart gramin bank
- Aryavart gramin bank solar loan
- Aryav Green Energy Private Limited
- Ashivini Kumar
- Ashok Gehlot
- Ashok Jhunjhunwala
- Ashok Patil
- Ashvini Kumar
- Asia
- Asia Energy
- Asian Development Research Institute
- Asian Fab Tec Limited
- Asian Global Infra Pvt Ltd
- Asia Pacific
- Aslam Mehan
- Assam
- Assessment and Collection of Anti-Dumping Duty on Dumped articles and for Determination of injury
- Asset Management
- association of power producers
- Astonfield
- Astonfield India
- Astonfield Solar II Private Limited
- Aston Greens Private Limited
- Aston Martin
- AT&C
- atikokan generating station
- Atlantic
- Atlantis Tidal Power
- atlas centre
- ATM
- Atoll
- Atomic Energy Commission
- Atomic Energy Regulatory Board
- Auckland Jute Mills Pvt Ltd
- Auction
- Augni Renewable Energy System India Private Limited
- August
- Aurora Colorado
- AusAID Public Sector Linkages Program
- australia
- australian government department
- Austria
- Automotive industry
- Auto rickshaw
- Avaada Power Private Limited
- availability
- Availability Based Tariff
- Average Cost of Supply
- Average Pooled Power Purchase Cost
- aviation
- Azerbaijan
- Azure
- Azure Power
- Azure Power (Rs 4.38)
- Azure Power India Private Limited
- Azure Power India Private Ltd
- Azure Power India Pvt. Ltd.
- Azure Power Karnataka Private Limited
- Azure Power Ltd.- New Delhi
- AZURE SOLAR PRIVATE LIMITED
- Azure Surya Pvt. Ltd.
- B.E.S.T
- Backbone Enterprise Ltd.
- Back Down
- back sheet adhesion loss
- Backsheets
- Badarpur Thermal Power Plant
- Bagasse
- Bagasse Cogeneration
- bailout plan
- Bajaj Hindustan Ltd.
- Banco Construction Pvt Ltd
- Bangalore
- Bangladesh
- Bangladesh Solar
- Banjara Hills
- bank guarantee
- Bank Guarantees Encashed
- banking
- banking charges
- banking facility for wind energy producers
- bank of India
- Bankrupt
- Bankruptcy
- Bankrupt DISCOMs
- banks financial institutions
- Baoding Tianwei Yingli New Energy Resources
- Baoding Tianwei Yingli New Energy Resources Co Ltd
- Baoding Zhongtai New Energy Resources Co Ltd
- Barack Obama
- Barker
- Barnhart
- Base Load Replacement Solutions
- Batch 2
- Batch III
- Batter
- batteries
- batteries for electric vehicles
- Battery
- Battery (electricity)
- Bavaria
- bavarian alps
- Bawana
- Beacon Power
- Beijing
- Belarus
- Belectric Photovoltaic India Pvt. Ltd.
- Benara Bearings & Pistons Limited
- Benchmark Capital Cost Norm
- Benchmark Capital Cost Norm for Solar PV power projects for the year 2015-16 (Petition No. SM/005/2015 ‐Suo‐Motu)
- Berkeley Lab
- berkeley lab scientists
- berkeley national laboratory
- berkeley university
- Berlin
- Bernhard Beck
- BertrandPiccard
- BESCOM
- Bessemer Venture Partners
- BEST
- BEST Depot
- BEST DISCOM
- BEST Mumbai
- BEST Mumbai Solar
- Best Practises
- Beta Renewables
- BGR
- Bhadaskonda
- Bhadla phase-III
- Bhadla solar park in Rajasthan
- Bhadresh Power Trading Corp.- New Delhi
- Bhagyanagar India Ltd
- Bhamri Enterprises
- Bharat Bhushan
- Bharat Petroleum Corporation Ltd.
- Bhatpara Township Substation
- Bhoruka Power Corporation Limited
- Bhubaneshwar Municpal
- Bhupinder Singh
- Bhutan
- bid
- Bid Bond
- Bidder
- bidding
- Bidding Consortium
- Bid price
- Bihar
- Bihar Solar Policy
- Bihar Solar RfP
- bikram singh
- Bill Gates
- Billion Units
- bio-remediator
- Bioenergy
- bioenergy systems
- Biofuel
- Biofuel Policy
- Biofuels
- Biofuels and waste
- BioGas
- Biogas based Power Project
- Biogas based Power Projects
- Biomass
- Biomass(non-bagasse) Cogeneration
- Biomass Blog
- Biomass blog india
- biomass energy
- Biomass Gasifier
- Biomass Gasifier based Power Projects
- Biomass Gasifier Power Projects
- Biomass Gasifiers
- Biomass Gassifier
- Biomass India
- Biomass Plantations
- Biomass Power
- biomass power plants
- Biomass Power Projects
- Biomass Power Projects(other than rice straw) with water cooled condenser
- Biomass Power Projects with Rankine Cycle technology
- Biomass Power with Rankine Cycle
- Biomass Rajasthan
- biomass rec
- Biomass Tariff
- BioPower (Biomass & Gasification and Bagasse Cogeneration)
- BIS
- BIS approval
- BJP
- Black Wafer
- blog
- Bloomberg
- blowing in the wind
- BLP
- Bluearth energy Pvt Ltd
- Blue Wafer
- BMW
- BNEF
- bob ferguson
- body corporates
- Boeing
- Bokaro Power Supply Company Pvt. Ltd.
- Bombay
- Bonds
- Bonn
- bonneville power administration
- Boond Engineering And Development
- BOOT Model
- Bosch
- Bosch Limited
- Bosch Ltd Bangalore
- Bosch Solar Energy
- Boston
- both solar
- BP
- Brahmaputra River
- Brandenburg
- Brandon Mitchener
- Brasil
- Brazil
- Breaks
- Bridge to India
- Brieuc
- Bright solar Ahmadabad
- BrihanMumbai Electricity Supply and Transport (BEST)
- Brihanmumbai Electric Supply & Transport Undertaking
- Brihanmumbai Electric Supply & Transport Undertaking (BEST)
- Brilliance Auto
- Britain
- Brown Coal
- BRPL
- BSES
- BSES official
- BU
- Buckminsterfullerene
- Budget
- Budget 2017
- Buksh Foundation
- Bundelkhand
- Bureau Indian Standards (BIS)
- burn marks
- busbars
- Business
- Business and Economy
- BusinessGreen
- Business Insider
- Business Line
- business opportunities
- Business plan
- Buyer
- B V Jagdish of Hiriyur
- ByD (Shangluo) Industrial
- BYPL
- C&I
- C& S Electric New Delhi
- C-Max Energi
- c-Si cell-to-module (CTM)
- C.Narasimhan
- Cabinet Committee on Economic Affairs
- cable system
- Cadillac
- Cadillac Converj
- cadmium chloride
- Cadmium Telleride
- Cadmium Telluride
- CalCEF Clean Energy Angel Fund
- California
- California Institute of Technology
- California Public Utilities Commission
- California PV solar
- California Solar Initiative
- Calypte Advisors LLP
- Cambodia
- Cambridge Energy Resources Pvt. Ltd.
- Canada
- Canadian Solar
- Canadian Solar (Changshu)
- Canadian Solar (Luoyang)
- Canadian Solar Energy (Rs 3.39)
- Canal
- Canal Banks
- canals
- Canal Top
- Canberra
- Cantabria
- capacitor banks
- capacity
- capacity addition
- Capacity Utilisation Factor (CUF)
- CAPEX
- Capital cost
- capital subsidies
- Capital Subsidy Scheme
- Captive
- Captive/ Group Captive
- Captive Compliance Requirement
- Captive Power Use
- carbon
- Carbon Capture
- Carbon capture and storage
- Carbon dioxide
- carbon dioxide emissions
- carbon dioxide gas
- Carbon dioxide in Earth's atmosphere
- carbon emissions
- carbon footprint
- Carbon PV Cell
- carbon target
- carbon tax
- carcinogen
- Carcogenic
- Care
- Care Rating
- carl pope
- cars
- cash and cash equivalents
- Castilla
- Catalonia
- catastrophic levels
- Catholic Church
- CCCME
- CCDC
- CCS
- CCTV
- CDPHE
- CdTe
- CEA
- CEEG (Shanghai) Solar Science Technology
- CEEG Nanjing Renewable Energy
- CEEW
- CEEW.IN
- ceiling fans refrigerators
- CEL
- cell
- cell cracks
- Cellular Base Stations
- cellulosic biofuel
- Cellulosic ethanol
- Celsius
- CEM
- center for biological diversity
- Center for International Environmental Law
- Central / State / Private Generation Companies
- central act
- Central Board of Excise and Customs (CBEC)
- central electricity
- Central Electricity Authority
- Central Electricity Authority (CEA)
- Central Electricity Authority India
- Central Electricity Regulator Commission
- central electricity regulatory commission
- Central Electricity Regulatory Commission (Terms and Conditions for Tariff determination from Renewable Energy Sources
- Central Electronics Ltd
- central element
- Central Eletricity Regulatory Commission
- Central Europe
- Central Financial
- Central Financial Assistance
- Central Government
- Central Information Commission
- central statistics office
- Centre for Science and Environment
- Centre for Wind Energy Technology
- Centrosolar
- CEO
- CEO at Hero Future Energies
- CEO of CEEW
- CERC
- CFA
- CFL
- CGP
- chaina
- chains
- Chairman
- Chaitanya Godavari Bank
- Chandigarh
- Chandrashekhar Bawankule
- Changzhou Trina Solar Energy
- Channel Partner
- Channel Partners
- Charanka
- Charanka Solar Park
- Charcoal
- charge
- Charitra Jain
- Charles David Keeling
- Chattisgarh
- cheap solar panels
- chemistry
- Chemtrol
- Chemtrols Mumbai
- Chemtrols Solar Pvt Ltd
- Chengdu Yingli New Energy Resources Co Ltd
- Chennai
- Chevrolet
- Chevrolet Volt
- chevron
- chevy volt
- Chhattisgarh
- Chhattisgarh (Govt. of Chhattisgarh & CSERC)
- Chhattisgarh Solar Policy
- chief engineer
- Chief Minister
- Chief Minister of Kerala
- Chief technology officer
- China
- China Development Bank
- china electric cars
- China PR
- China Sunergy
- china sunergy co
- Chindia
- Chinese
- chinese banks
- chinese chamber of commerce
- chinese exporters
- Chinese government
- chinese importers
- Chinese imports
- Chinese language
- Chinese New Year
- Chinese Solar Manufacturers
- Chint Solar (Zhejiang)
- chlor alkali sludge
- Chong Quan
- Christian Democratic Union
- Christopher Bardeen
- Chris Wheaton
- CIGS
- CIS
- CISCONS Projects Pvt Ltd
- CIS thin-film solar modules
- Citi
- Citigroup
- Clarifications
- Class Action
- class action lawsuit
- Clean Air
- clean air act
- Clean Development Mechanism (CDM)
- clean electricity
- clean energy
- CleanEnergy
- Clean Energy Cess
- Clean Energy Ministerial
- clean energy technologies
- Clean Max Enviro Energy Solutions Pvt Ltd
- Clean power Research
- Clean Solar Power (Chitradurga) Pvt Ltd
- Clean technology
- climate
- Climate Change
- climate scientists
- Climatescope
- close
- CNC
- CNG
- CNOOC Limited
- co-founder and CTO of Heliatek
- co-founder of Heliatek
- CO2
- Coal
- coal-fired
- Coal and Lignite
- coal auction
- Coal Cess
- coal combustion
- coal consumer
- coal consumption
- coal demand
- coal gas
- coal india
- coal india ltd
- Coal Mafia
- Coal Mines
- coal plants
- coal power
- Coal Power Plant
- Coal Power plant affected soil
- Coal Power Plants
- coal prices
- coal regulatory authority bill
- Coal replacement
- Coast
- Cochin Airport
- Cogen
- CoGeneration
- cogeneration power plants
- Coimbatore
- Coimbatore power crisis
- Coimbatore power cuts
- Coke Solar Coolers
- Cold chain
- cold storage facilities
- cold storages
- cold tank
- collaboration
- Colorado
- colorado department of public health
- colorado department of public health and environment
- combination
- Combined Heat and Power
- Commerce ministry
- Commercial Banks
- commercial consumers
- commercial entities
- commercial establishments
- Commerciall Losses
- Commercial Rooftop
- commercial scale installations
- Commission
- commissions
- commodity pricing
- Company
- Company Limited
- Competition
- competitive bidding process
- compliance monitoring
- compliance rules
- Compressed air energy storage
- Compressed natural gas
- Concentrated photovoltaics
- Concentrated Solar Power
- Concentrating
- Concept car
- concept vehicle
- Concessional Custom Duty Certificate
- Concessional Customs Duty Certificate
- Concessional Customs Duty Certificates
- Concession Customs Duty Certificates
- Conclave
- Conclusions A mix of flexibility resources is needed to manage variability across all timescales This study explores the integration of variable renewables (VRE) beyond 70% share of annual generation.
- Conergy
- Confederation of Indian Industry
- conference
- Congress
- Consolidated financial statement
- constitution article
- CONSTRUCTION
- Consul Consolidate d Chennai
- Consumer
- consumer advocacy group
- consumption growth
- control period
- conventional asphalt
- conventional electricity
- conventional energy resources
- conventional energy sources
- Conventional Power
- conventional power generation
- conventional power plants
- conventional silicon
- conventional sources
- conversion efficiencies
- conversion efficiency
- Convertible bond
- Cooking
- Cooperation
- Copper
- copper electrodes
- copper indium
- Copper indium gallium selenide
- Coramandel Infrastructure Pvt Ltd
- CoS
- Cost
- Cost Analysis Solar
- Cost of electricity by source
- Cost of Service
- cost plus pricing of coal
- Cost–benefit analysis
- Council on Energy
- council vote
- countervailing duty
- couple
- Covasna
- cow manure
- CPDCL
- CPSUs MW
- CPV
- cranfield mississippi
- CREDA
- credit rating agencies
- Crescent Dunes
- Crescent Dunes Solar Energy Project
- Crescentino
- CRISIL
- Crisil Research
- CRMM
- Croatia
- Crompton Greave
- Cross Subsidy
- Cross Subsidy Charge
- Cross Subsidy Surcharge
- Crystalline
- crystalline silicon
- crystalline silicon cells
- CSE
- CSI
- CSP
- CSP Storage
- csp technology
- CSP Tower Technology
- CSS
- CSun
- CTM
- Cuenca
- CUF
- cumulative basis
- Cupertino California
- current account deficit
- customs and border protection
- customs code 8501
- customs code 8541
- Customs Duty
- Customs Duty Exemption
- Customs Tariff Act 1975
- Cuyahoga Valley Scenic Railroad
- CVK Solar Enterprises Private Limited
- CWET
- Czech Republic
- D.D. Project Services Pvt Ltd
- Dadhwal Solar Private Limited
- Dadra & Nagar Haveli
- Daily Normal Irradiance
- Dakshin Gujarat Vij Co. Ltd
- Dallas Texas
- Daman & Diu
- Data Source
- Datia
- Datia District
- Dave Camp
- DC
- DC Capping
- DCR
- Dead Sea
- Debt restructuring
- Decarbonisation
- Deemed Generation
- Deepak Gadhia
- Deepa Solar Bangalore
- deep cycle batteries
- Deep cycle battery
- defective bypass diodes; and special failures of thin-film modules
- De Gucht
- delamination
- Delaware Technical Community College
- Delhi
- Delhi (DERC order)
- Delhi Electricity Regulatory Commission
- Delhi Government
- Delhi Metro
- Delhi Solar PV
- delivery point
- Deloitte
- Delsolar
- Delsolar (Wujiang)
- Delta Technology ft Management Services Pvt Ltd
- Demand Draft
- Demand response
- Department of Commerce
- Department of Energ
- Department of Energy
- Department of Financial Services
- Department of Industrial Policy and Promotion (DIPP)
- departments
- deployed
- deploying
- Deployment
- deputy chief minister
- Dera Ghazi Khan
- DERC
- Deshmukh Electrical Consultant Private Limited
- Detailed Drawings
- Deutsche Bank
- Developer
- developers
- Developing
- development
- development control rules
- develops
- Devendra Fadnavis
- Devendra Kumar
- Devendra Kumar Pant
- deviation charges
- deviation settlement
- Dexler Holdings Pvt Ltd
- DGAD
- Dhanep
- DHL
- Dhoodsar Village
- D H Umesh of Gadag
- Diesel
- diesel consumption
- Diesel generator
- Diesel Replacement
- Diesel Vehicles
- Dilip Gupta
- Dilip Nigam
- Dinesh Kumar Changani
- Direct current
- Direct normal irradiance
- Direct normal irradiance Map
- Direct normal irradiance Map India
- Directorate General of Safeguards Customs and Central Excise
- Dirty Energy
- DISCOM
- Discom Bailout
- Discom Losses
- Discom Penalty
- Discoms
- disconnected cell and string interconnect ribbons
- dispute settlement body
- disruptive innovation
- Distributed Energy
- Distributed Generation
- Distributed grid generation
- Distributed Local Generation
- Distribution
- distribution corporation
- distribution sector
- distribution segment
- Distribution Utilities
- District Central Cooperative Banks
- District hrat
- Divyakshetra Infra Pvt Ltd
- DIY Solar
- DJ Pandian
- D J Pandian
- DK Infracon Pvt. Ltd
- D K Shivakumar
- D Mahesh of Koppal and Basappa K Pattanashetty of Sindhanur
- DMRC
- DNI
- DNRE
- DNV GL
- DOE
- Doha
- domestic coal
- domestic competitors
- domestic consumers
- Domestic Content Requirement
- Domestic Content Requiremnt
- Domestic Content Route
- domestic manufacturers
- domestic producers
- domestic support measures
- Down to Earth
- Dr. D.N. Singh
- Dr. Martin Pfeiffer
- Dr. P.Rambabu
- Dr. Pravin Chordia
- Draft Guidelines
- draft regulations
- dr farooq abdullah
- drive turbines
- dr manmohan singh
- Dubai
- Duke Energy
- Dumping
- Dumping (pricing policy)
- dumping duties
- DuPont
- Dusseldorf
- DVD
- dynamic effects of wind for large-scale Solar PV Plants
- E.ON
- EAAMA Estates Pvt Ltd
- Eagle Infra India Ltd
- earnest money deposit
- Earnings before interest and taxes
- earth day network
- earth sciences division
- Earth system
- Eastern power Distribution Company of A.P. Ltd
- Eastern Time Zone
- Eastern Washington
- Ecology
- Economic Co-operation and Development (OECD) countries
- Economic system
- economy
- EDEC
- EDF
- Ed Grady
- Edison Electric Institute
- EDP
- EDPR
- Efficiency
- Efficient energy use
- Efi Arazi
- EIB
- Eknath Solkar
- El-Sol Energy Ahmadabad
- El-Sol Energy Systems
- ele
- Electric
- Electrical grid
- Electrical load
- Electrically
- Electrical Storage
- Electrical Transformer
- Electric Buses
- Electric car
- Electric Car Batteries
- Electric Cars
- Electric Charger
- Electric double-layer capacitor
- Electric energy consumption
- Electric generator
- electric grid
- Electric Hybrids
- Electricity
- electricity act
- Electricity Act 2003
- electricity authority
- electricity board
- electricity charges
- electricity consumers
- electricity consumption
- electricity distribution companies
- Electricity Duty
- Electricity from CO2
- electricity from sunlight
- electricity generated
- Electricity generation
- electricity generation systems
- electricity grid
- electricity policy
- Electricity prices
- electricity regulator
- electricity regulators
- electricity regulatory commission
- Electricity sector in India
- electricity tariffs
- Electric Power
- Electric power distribution
- electric power generation
- Electric power transmission
- Electric Storage
- Electricty Storage
- Electric vehicle
- Electric Vehicles
- Electrode
- electrolysers
- electron
- electrons
- El Niño
- Elon Musk
- ELR
- Emami Cement-Kolkata
- Emami Cement Ltd.
- Emami Power Limited
- Emami Power Ltd
- Embedded Cost Methodology
- EM Bypass
- Emeral Energy Ahmadabad
- emission
- Emission intensity
- Emissionsin
- EMMVEE Solar
- Emmvee Solar Photovoltaic
- Empa
- empanelled Chartered Engineer
- Empire Photovolatic System Private Limited
- Employment
- Empower plans
- Enercon
- energetica
- Energi
- energies
- Energo Engineering Projects Ltd
- Energon Solar (100 MW)
- Energon Soleq Ravi India Power Resources Pvt Ltd
- energy
- Energy & Environmental Science
- Energy Action
- Energy and Economy
- ENERGY AND LABOUR DEPARTMENT
- Energy and Resources Institute
- Energy Banking
- Energy Charges
- energy commodities
- energy commodity pricing
- Energy conservation
- Energy Consumption
- Energy Conversion Devices
- energy conversion efficiency
- Energy crisis
- Energy demand management
- Energy development
- Energy Development Company Ltd.
- energy devices
- energy economics
- energy economies
- energy efficiency companies
- energy efficiency improvements
- energy generators
- Energy Goals
- Energy Independence
- Energy India
- energy industries association
- Energy industry
- energy information administration
- energy management system
- Energy Next
- Energy Plantations
- Energy plays
- Energy policy
- Energy Poor
- energy production
- energy progress
- energy provision
- Energy returned on energy invested
- energy risks
- Energy Saved
- energy scene
- Energy security
- energy service company
- energy share
- Energy Solar
- Energy Statistics
- Energy Storage
- energy storage capacity
- Energy Storage Study
- energy storage system
- energy storage systems
- energy supplier
- Energy system
- Energy technology
- energy transition
- energy utility companies
- energy yield
- ENERGY YIELD PREDICTION
- Enersan Power Pvt. Ltd.
- enewable capacity
- ENFIELD INFRASTRUCTURE LIMITED
- Enfield Solar
- Enfrosun Power Private Limited
- engineering
- engineering lines
- Engro Corporation
- Enphase Energy
- Enrich Energy Private Limited
- Enrich Energy Pvt Ltd Pune
- entities
- environment
- environmental activists
- environmental pollutant
- Environment and Water (CEEW)
- environment impact assessment
- EON
- Eoxis
- EPC
- EPC CONTRACTS
- EPDCL
- EPIA
- Equinor
- Er. Lalit Kaushik
- Eric Brewer
- Eric Martinot
- Ernst & Young
- escalation factors
- ESD Builders and Developers Private Limited
- ESG
- Eskom
- Essar Group
- Essel Infra
- Essel Infraprojects Limited
- Essel Infraprojects Ltd.
- Essellnfraprojects Ltd.- Mumbai
- Essel Mining and Industries Ltd
- ESSEL MP ENERGY LIMITED
- Essen
- Establishments
- Establishments of Army
- etc.
- Ethanol
- ethylene
- EU clean
- eu member states
- Euro Multivision Ltd.
- europe
- European Commission
- European Commissioner for Energy
- European Commissioner for Trade
- European Environmental Agency (EEA)
- European Patent Convention
- european producers
- European Union
- European Union Emission Trading Scheme
- european union member states
- Europe the Middle East and Africa
- Eurosolar
- Eurostat
- EV
- EVA
- EVA discolouration
- Evelyn Wang
- event
- Events
- Evergreen
- Eversun Energy Bangalore
- EV Report
- excessive profits
- Excise Duty Certificate
- excise duty exemption
- Excise Duty Exemption Certificate
- Excise Duty Exemption Certificates
- Excise Exemption
- excited state
- excitons
- Executive Director
- Exemption
- Exicom Tele Gurgaon
- Expert Committee
- Exploring
- ExxonMobil
- F.No. 6/30/2017-DGAD
- Fahrenheit
- failure mode and effect analysis
- failure rates
- fake power purchase agreements
- false allegations
- Fame
- Fame 2019
- Fame II
- Family Biogas Plants (in Lakhs)
- Faridabad
- Farmer
- Farmer PPA
- Farmers
- Farmers Producers Organisation
- Farooq Abdullah
- Farroq Abdullah
- fastest growing segment
- fault tree analysis
- FDI
- Federal Network Agency
- federal subsidies
- federal tax incentives
- Feed-in tariff
- feed-in tariffs
- feedintariffs
- Feedstock
- fermentation process
- Fiat
- Fibremarx Papers Pvt. Ltd.. Kashipur. U.K.
- FICCI
- finance
- Finance Ministry
- finances
- finance secretary Hasmukh Adhia
- financial closure
- financial credibility
- financial restructuring
- financial viability
- FINANCING SOLAR PV POWER PROJECTS
- Finland
- Finnsurya Energy Pvt Ltd.
- Firstgreen Consulting Pvt Ltd
- First Solar
- First Solar Power India Pvt Ltd
- Fiscal year
- fit
- Fixed Tilt Mounting Structure
- Flexible Solar Cells
- Floating Solar Plant
- Floor Price
- Florida plant
- Flow battery
- Fluid Engineers
- Fly Ash
- fly ash dumps
- Focal Energy Solar India PVt. Ltd
- Focal Energy Solar Pvt. Ltd.- Cyprus
- Fonroche Energies (100 MW)
- FONROCHE RAAJHANS ENERGY PRIVATE LIMITED
- FONROCHE SAARAS ENERGY PRIVATE LIMITED
- Fonroche Saaras Energy Pvt. Ltd Mumbai
- Food Resource
- food shortages in india
- Forbearance Price
- Ford
- Ford C-Max
- Ford Fusion
- Ford Motor Company
- forecasting
- Forest
- forest conservation act
- Forests
- Forests and Climate Change (MOEFCC)
- Forest Waste
- forex
- Fortum Finnsurya Energy Pvt Ltd
- Fossil-fuel power station
- Fossil fuel
- fossil fuel power plants
- fossil fuel reserves
- Fossil Fuels
- fossil fuels decline
- Fossil Fuel Subsidies
- Fossil Fuel Subsidy
- Fourth Partner Energy Pvt Ltd
- Fourth Partner Energy Pvt Ltd Hyderabad
- Fracking
- frame breakage
- France
- Frankfurt
- Franklin College of Arts and Science
- fraunhofer
- fraunhofer ise
- Fraunhofer Society
- free developers
- freedom of speech
- Freyr Energy Services Private Limited
- Friday
- Friends Salts Works Allied Industries- Gandhidham
- Front Companies
- front glass breakage
- FRV Solar Holdings XI BV
- FSLR
- Fuel
- Fuel cell
- fuel cell record efficiency
- Fuel Cells
- Fuel Cell Technology
- fuel mix
- Fuels
- Fuelsupply
- Fukushima
- Fukushima Daiichi
- Fukushima Daiichi nuclear disaster
- Fukushima Daiichi Nuclear Power Plant
- Fukushima Disaster
- Fukushima Nuclear Crisis
- Fukushima Nuclear Plant
- Fukushima Radiation
- fundamental right
- Funding
- Furnace Oil
- futures report
- G.B. Nayak
- Gabon
- GAIL (INDIA) Limited
- Gajanan Financial Services Private Limited
- Gallium
- gallium arsenide
- game changer
- Gamesa
- Gandhinagar
- Gap
- Garbage
- garbage dump
- Gas
- Gas based electric cars
- Gas Electric Hybrid
- gaseous hydrogen
- Gas Hybrids
- Gasification
- Gasoline
- Gas prices
- Gateway Energy
- Gautam Solar
- GBI
- GCC
- GCL
- GCL-Poly
- GE
- Gears Energy Solution Private Limited
- GEDA
- GE Global Research
- Gehrlicher
- Gehrlicher Solar
- Gehrlicher Solar AG
- gemasolar
- Genco
- General Carbon Advisory Group
- General Electric
- Generally accepted accounting principles
- General Motors
- Generation
- Generation Based Incentives
- generation of electricity
- generations
- Gensol Consultants Private Limited
- Gensol Engineering Private Limited
- Genus Innovation Ltd
- geophysical
- Geopower India Private Limited
- George Adamson
- Georgia Institute of Technology
- Georgia Institute of Technology College of Sciences
- Georgia Power
- Geothermal
- Geothermal Energy Capacity
- GeoThermal India
- geothermal power plants
- GERC
- German
- German Climate Consortium
- german federal government
- german federation
- German government
- german industry
- German KfW Development Bank
- German language
- German reunification
- Germany
- Germany Record Generation
- GESCOM
- getco
- GE Vernova announces 1.4 GW of onshore wind projects with Squadron Energy in Australia
- Ghaziabad
- GHG
- GHI
- Giant King Grass
- gigawatts
- Gireesh Pradhan
- Giriraj Renewables Private Ltd
- girls
- GKC Projects Limited
- glaciers
- Gladstone
- Glass
- glass melting furnaces
- GlassPoint
- global
- Global Atlas
- global capacity
- global carbon dioxide
- Global CCS Institute
- Global CCS Institute study
- Global Climate and Energy Project
- global co2 emissions
- global demand
- global energy consumption
- global energy system
- global fossil fuel
- Global Hydrogen
- global installations
- Globally
- Global Needs
- Global PV
- Global PV Supply
- Global Solar Report
- Global Status Report
- global temperatures
- Global warming
- global warming and climate change
- globe
- Glossary
- Glossary of chess
- gmr
- GMR Group
- Goa
- goal
- goals
- Godawari
- Godrej & Boyce
- Godrej Mumbai
- goes
- Goggles Energy Private Limited
- GoK
- Golden Crystal Infrabuild Ltd.
- Goldi Green Technologies
- Goods and Service Tax
- Googleplex
- Gorges
- Government
- government assignments
- government entities
- government finalised
- government investigations
- government of andhra pradesh
- government of gujarat
- Government of India
- GOVERNMENT OF INDIA ENTERPRISE
- Government of Karnataka
- Government of Maharashtra
- government policy changes
- Governments
- government subsidy
- Government of India Organizations
- govt of india
- gpcl
- GP Eco Solutions India Pvt Ltd
- GPR Power Solutions Pvt Ltd
- grade
- Grameen Solar
- Gram Power
- Graphene
- grasim industries ltd
- Grass
- Green
- Greenalia
- Green Brilliance
- Green Buildings Division
- Green Eco Energy
- green electricity
- Green energy
- Green Energy Dev. Co. of Odhisha Ltd.
- green energy technologies
- Greenenergy Wind Corp Pvt. Ltd
- greener energy
- Greenergy Wind Corporation Private Limited
- Green First Power Ventures Pvt Ltd
- Greenhouse gas
- greenhouse gas emissions
- Greenhouse Gases
- green hydrogen
- Green Infra
- Green Infra Corporate Solar Ltd.
- GREEN INFRA SOLAR FARMS LIMITED
- GREEN INFRA SOLAR PROJECTS LIMITED
- Greenko Energies (Rs 4.09)
- green light
- Green News
- Greenpeace
- green power projects
- green shipping
- Green Tariff
- Greentek India Pvt Ltd
- Grid
- Gridco Corporation
- Grid connected
- Grid Connected Rooftop and Small Solar Power Plants Programme' (vide no. 30/11/2012-13/NSM dated 25th June
- Grid Connected Rooftop Solar PV System
- Grid Connection
- Grid Connect Solar PV Power Projects
- Griddy
- grid electricity
- grid failure
- Grid Independence
- grid integration socio-economic aspects
- grid interactive
- Grid Parity
- Grid Solar PV power
- Grid Storage
- Grid Storage Systems
- Grid Transmission
- Grindwell
- Gross world product
- Ground-mount
- Group of Ministers
- GRT Jewellers (India) Pvt Ltd
- GRT Jewellers India Private Limited
- GST
- GST 18%
- GST Law
- GST Solar
- GTM Report
- GTM Research
- GuangDong Polytechnic Normal University
- Guidelines
- Guja
- Gujarat
- Gujarat (Govt. of Gujarat & GERC)
- Gujarat Alkalies and Chemicals Ltd.
- Gujarat Electricity Regulatory Commission
- Gujarat Electricity Regulatory Commission 2
- Gujarat Energy Development Agency
- gujarat government
- Gujarat Kutch
- Gujarat Phase III
- Gujarat Power Corporation Ltd
- Gujarat Renewable Energy
- Gujarat Solar
- Gujarat Solar Policy
- Gujarat Solar Policy Phase 3
- Gujarat Solar Power Policy
- Gujarat State Electricity Co. Ltd.
- Gujarat State Petroleum Corporation
- Gujarat Tidal Policy
- Gujarat Tidal Power
- Gujarat Urja Vikas Nigam
- Gujarat Urja Vikas Nigam Limited
- Gujarat Urja Vikas Nigam Limited (GUVNL)
- Gujarat Urja Vikas Nigam Ltd
- Gujarat Wind Policy 2013
- Gurgaon
- guvnl
- GVPR Engineers Limited
- GW
- Gwalior
- GyaneshChoudhary
- gözetim vergisi
- Günther Oettinger
- Hainan Yingli New Energy Resources
- Haizea
- Hamburg
- Hanford Site
- Hans-Joachim Queisser
- Hanwha
- Hanwha Q-Cells
- Hanwha SolarOne
- HanwhaSolarOne
- Hard coal
- Hardoi
- hardoi district
- HAREDA
- Harish Hande
- Harsha Abakus Solar Pvt Ltd
- Haryana
- Haryana (Govt. of Haryana)
- Haryana Chief Minister Bhupinder Singh Hooda
- Hasan Marketing Pvt Ltd
- HCPV
- heart wave
- heat
- Hefei Chinaland Solar Energy
- Hefei JA Solar Technology
- Heidelberg Solar Pvt Ltd
- Heliatek
- Helios Photo Voltaic Limited
- Helmholtz Zentrum Berlin
- Helmut Kohl
- hemlock semiconductor corp
- Hengerer
- HERC
- herd mentality
- Hero Future Energies (100 MW)
- Hero Future Energies Pvt Ltd
- Hero Solar Energy PVt. Ltd
- HESCOM
- Hetero Drugs
- HFM Solar Power Pvt Ltd
- HHV
- high efficiency
- Highground Energy Pvt Ltd
- High tech
- High Tension
- Himachal
- Himachal Pradesh
- Himachal Pradesh Electricity Regulatory Commission
- Himalayas
- Himgiri Energy Venture Pvt. Ltd.-Gwalior
- HIMURJA
- Hindalco
- Hindalco Ltd.
- Hindu
- hindu business line
- Hindustan Power Projects
- Hindustan Times
- Hindustan Zinc
- Hindustan Zinc Ltd.
- HIQ Power Associates Pvt Ltd
- HIRA Ferro Alloys Ltd
- Hitesh Doshi
- H Krishnappa of Haveri
- home improvement loan
- Home Lighting
- Home Loans
- Hongjie Dai
- Horace-Bénédict de Saussure
- Hot Climate
- hot water boiler
- hot water heating
- House
- household appliances
- household chores
- Household Generation
- household requirements
- Households
- HP
- HPERC
- HSBC
- HT2A
- HT2B
- HT2C
- Hubei
- Hugoton Kansas
- Hungary
- Hurricanes
- Hybrid
- Hybrid electric vehicle
- hybridisation
- hybridization
- hybrid projects
- Hybrids
- Hybrid vehicle
- Hyddrogen
- Hyderabad
- Hyderabad India
- Hydro
- Hydro Aluminum
- Hydrocarbon exploration
- Hydroelectricity
- hydroelectric power stations
- Hydro including Pumped Storage
- Hydro India
- Hydropower
- hydro power projects
- hydro rec
- Iacharya Silicon Ltd
- IAEA-PRIS
- IBM
- Iceland
- ICRA Management Consulting Services
- Identification
- IEA
- IEA Executive Director
- IEC/EVS EN 62446
- IEC/TR 60755
- IEC60364 – 7 – 712
- IEC 60364-6
- IEC 61557
- IEC 61730 – 1
- IEX
- IFC Report
- IHS
- IHS Inc
- IISc
- IITB
- IIT Madras
- IIT Mumbai
- IL&FS
- IL&FS-New Delhi (In Consortium with First Solar)
- ILF&S Energy Development Co. Ltd.
- ILF&S Renewable Energy Ltd.
- Illinois
- Illinois University
- image based methods
- imaps
- IMEC
- imperative requirement
- Implementation of Goods & Services Tax
- Implementing
- import/procurement of items/components
- Improved Grid Efficiency
- improving energy efficiency
- imran khan
- Incentive
- incentives
- Income Tax
- income tax act
- Incoterms
- incremental innovation
- independent analysis
- independent power producer
- Independent Power Producers
- independent subsidiaries
- India
- India's largest industrial solar thermal plant
- india cement
- India Coal Plants
- India electric cars
- india enterprise
- India Government of India
- India GST
- India hybrid vehicles
- india india
- India Infrastructure Finance Corporation
- Indian Armed Forces
- Indian Army
- Indian Budget 2017
- indian cement industry
- Indian Energy
- Indian Energy Exchange
- indian energy sector
- Indian government
- Indian government auction
- Indian Grid Failure
- indian institute of technology madras
- Indian National Institute of Solar Energy (NISE)
- Indian Penal Code (IPC) 420
- Indian Petrochemical Company Ltd.
- indian power sector
- Indian Sol
- Indian solar industry
- Indian Solar Manufacturers
- Indian Solar Manufacturers' Association
- Indian Solar Manufacturers Association (ISMA)
- Indian Solar Summit
- Indian state solar policy
- Indian village powered by solar
- Indian Wind Energy Association
- Indian Wind Energy Association (InWEA)
- Indian Wind Turbine Manufacturers' Association (IWTMA)
- India Power
- India power investments
- India PV
- india report
- India Solar
- India Solar Blog
- india solar growth
- India Solar Map
- India Solar Policy
- India Solar Power
- India Solar Status
- India Today Fraud Lanco
- India’s Ministry of Environment
- Indigenous
- Indium
- Indium gallium arsenide
- indium tin oxide
- Indo-Asian News Service
- Indo NationalLtd
- Indonesia
- Indore
- Indosolar
- Indo Solar
- Indosolar Limited
- Indosolar Ltd.
- Indraprastha Gas
- Industrial
- industrial effluents
- industrial sectors
- industrial technology development
- INDUSTRIES
- Industry
- Industry Power Tariff
- inefficient Discoms
- Infigen Energy
- Infographics
- information platform
- information technology
- Inland Empire
- innovation
- Innovative Roof Solar Solutions Llp
- inorganic semiconductor
- Insolation
- Insolvency
- Inspira Enterprise India Pvt. Ltd.
- Installation
- installation areas
- Installed capacity
- Installed Solar Capacity
- installtion
- institution of mechanical engineers
- Insurability
- Insurance
- Integrated Engineers & Consultants Pvt Ltd
- Intellectual property
- Intergovernmental Panel on Climate Change
- intergovernmental panel on climate change ipcc
- internal combustion
- international auto show
- international energy agency
- International Energy Agency (IEA)
- international energy company
- international finance corporation
- international investment bank
- International Marketing
- International Marketing Corporation
- International Monetary Fund
- International Renewable Energy Agency
- International Renewable Energy Agency (IRENA)
- International Solar Alliance
- Introduction
- Inverter
- Inverters
- Invertors
- Investment
- investments
- InWEA
- IPad
- IPCC
- IPCC report
- iPhone
- IPP
- IPPs
- Iraq
- IREDA
- Ireland
- IRENA
- IRENA Report Renewable Jobs
- irradiance
- Irrigation
- irrigation project
- irrigation requirements
- Irwin Texas
- Isma
- is on the verge of becoming obsolete. Local demand for these modules continues to dwindle and is expected to last for another 1-2 years. On the brighter side
- Israel
- Italian project
- Italy
- IV Curve
- IWTMA
- J&K
- J.K. Lakshmi Cement Ltd.
- J.S.W. Steel Limited.
- JA
- Jaagruthi Power ft Infra Pvt Ltd
- Jackson Ltd
- JACKSON POWER PVT. LTD.
- Jacob Dickinson
- Jadav
- Jadav Payeng
- Jai Irrigation Jalgaon
- Jai Mata Di Solar Energy Pvt Ltd
- Jain Irrigation
- Jain Irrigation System
- Jain Irrigation Systems Ltd-Gulbarga
- Jain Irrigation Systems Ltd-Mangalore
- Jain Irrigation Systems Ltd-Udupi
- Jaipur Vidyut Vitran Nigam
- Jai Rathod
- Jaisalmer
- Jaiswal batteries Lucknow
- Jaiswal Battery Services
- Jakson
- Jakson Engineers Limited
- Jakson Engineers Ltd
- Jakson engineers Noida
- Jakson Power Pvt. Ltd
- Jakson Solar Pvt. Ltd.
- Jalaun district
- Jamabandi
- James Maynard
- James Montgomery
- Jammu & Kashmir and Lakshadweep
- Jammu and Kashmir
- January 2012
- Japan
- Japanese
- Japan Fukushima
- Ja Solar
- JA Solar Technology Yangzhou
- jawaharlal nehru
- Jawaharlal Nehru National Solar Mission
- Jawaharlal Nehru National Urban Renewal Mission
- Jawaharlal Nehru Solar Mission
- Jawarharlal Nehru National Solar Mission
- Jay Lewis
- jeffrey grossman
- JERC
- Jessika Trancik
- Jharkhand
- Jiangsu Yingli New Energy Co Ltd
- Jiangxi LDK Solar Hi-Tech
- Jianhsu Seraphim Solar System
- Jim Doyle
- Jim Hughes
- Jindal Aluminium Ltd
- Jindal Power
- Jindal Steel and Power Ltd.
- JingAo Solar
- Jinko
- JinkoSolar
- Jinzhou Huachang Photovoltaic Technology
- Jinzhou Jinmao Photovoltaic Technology
- Jinzhou Rixin Silicon Materials
- Jinzhou Yangguang Energy
- Jinzhou Youhua Silicon Materials
- Jitendra Singh
- J Jayalalithaa
- JJ PV Solar
- JJ PV Solar Pvt Ltd
- J K Petroenergy Pvt Ltd
- JNNSM
- JNNSM Phase
- JNNSM Phase 1 Batch 1
- JNNSM Phase 1 Batch 2
- JNNSM Phase 2
- JNNSM Phase 2 Batch 2
- JNNSM Phase I Batch II
- JNNSM Phase II
- JNNSM Projects
- jodhpur
- Jodhpur Vidyut Vitran Nigam
- Joe Lieberman
- Johanna Wanka
- John F. Kennedy International Airport
- John McCain
- Joint Center for Artificial Photosynthesis
- Joint Energy Regulatory Commission
- Joint Secretary
- Jorhat
- Joseph Fourier
- Journal of Physical Chemistry Letters
- JSW Energy
- judicial probe
- July 2011
- July India Blackout
- junction box failure
- Jupiter Solar
- Jupiter Solar Power Limited
- Jupiter Solar Power Ltd
- Justices Sanjiv Khanna and Chander Shekhar
- justification of requirement of cable
- juwi
- Kadapa
- Kadapah
- Kadapa Solar Park
- Kalthia Engineering And Construction Ltd
- Kanchi Surya Power Pvt Ltd
- Kandla Port Trust
- Kapoor
- Karel De Gucht
- Karl Kruszelnicki
- Karl Kuhlmann
- Karmasukom Energy
- Karnataka
- Karnataka (Govt. of Karnataka & KERC)
- Karnataka Electricity Regulatory Commission
- Karnataka Electricity Regulatory Commission (KERC)
- Karnataka government
- Karnataka Power Corporation Ltd.
- karnataka solar
- karnataka solar bids
- Karnataka Solar Farmer PPA
- Karnataka Solar Policy 2014 - 2021
- Karnataka Solar Policy 2014-21
- Karnataka State Biofuel Development Board
- Kashmir
- Kassel
- Kavit Industries Limited
- KBS Certification Service Private Limited
- K Chandrasekhar Rao
- KEC International limited
- Kenersys
- Kerala
- Kerala (Govt. of Kerala & KERC)
- kerala chief minister
- Kerala Council of Ministers
- Kerala Electricity
- Kerala Power
- Kerala Rooftop Policy
- Kerala Solar
- Kerala Solar Policy
- Kerala Solar Subsidy
- Kerala State Electricity Board
- Kerala State Electricity Regulatory Commission
- KERC
- kerosene lamp
- kerosene lamps
- Key
- Khaga Solar Pvt Ltd
- K H Guruswamy of Madhugiri
- Khosla Ventures
- Khyber Pakhtunkhwa
- kilowatt hour
- Kiran Energy
- kiran kumar
- Kirloskar Integrated Tech
- Kiwa
- KKDK Energy Infrastructure Private Limited
- K Kumar Raja Projects (P) Ltd
- K L Lokesh of KGF
- KL Solar
- KM Power Pvt Ltd
- K N Subramaniam
- Kolkata
- Korea
- Kotak Urja Pvt. Ltd.
- KPMG
- KPMG Rising Sun 2012
- KRBL-Indore
- KREDL
- Krishnagiri
- Krishnagiri district
- Krishna Godavari Basin
- krishna rao
- K R K Power Private Limited
- KSERC
- KSK Energy Ventures Limited
- KSK Energy Ventures Ltd.
- KSREC
- kulim malaysia
- Kunitomi Japan
- Kurzweil
- KUSUM
- kv transmission lines
- Kwatt Solutions Pvt Ltd
- kWh
- KWp
- Kyocera
- Kyrgyzstan
- Ladakh
- lakes
- Lakshadweep
- Lalit
- Lalit Soni
- lanco
- Lanco Group
- Lanco Infra
- Lanco Infratech
- lanco infratech ltd
- Lanco Solar
- Lanco Solar Energy Private Limited
- Land Down Under
- Landslide
- Larry Page
- Larsen & Toubro
- latest technological advances
- Latin America
- lawrence berkeley laboratory
- Lawrence Berkeley National Laboratory
- Laxmi Diamond Pvt. Ltd.
- LCOE
- ldeaspace Solutions Limited
- LDF
- LDK Solar
- LDK Solar Co
- LDK Solar Hi-Tech (Hefei)
- LDK Solar Hi-Tech (Nanchang)
- LDK Solar Hi-Tech (Suzhou)
- lead sulfide
- Lead–acid battery
- LED
- Left Democratic Front (Kerala)
- LEPL PROJECTS LIMITED
- Leuven
- Levellised Fixed Cost
- Lewis
- LEXICON VANIJIYA PRIVATE LIMITED
- Lexicon Vanijya Pvt Ltd
- LGBR
- Libra Solutions
- LiB supply chain
- licensee
- LICENSING AND ENVIRONMENTAL CONSIDERATIONS
- LiFE
- Light-emitting diode
- light energy
- Lighting
- lighting energy
- Lighting Systems
- Lignite
- LiIon
- Li Juntao
- Limbarvadi
- linear view
- Liquefied natural gas
- Lisbon
- List of banks in the People's Republic of China
- List of companies of India
- lithium ion batteries
- lithium ion battery
- livelihood generation
- living with power cuts
- Lixian Yingli New Energy Resources Co Ltd
- LNG
- lnspira Enterprise India Pvt Ltd
- lnspra Enterprises Pvt. Ltd.- Mumbai
- lnterocean Shipping (India) Pvt Ltd
- Load-shedding
- load flow analysis
- Load Generation Balance Report
- LOAD GENERATION BALANCE REPORT 2016-17 - Central Electricity Authority
- Loading Codes
- location state
- Lodhi Road
- logistics
- Lok Sabha
- London
- london school of economics
- long-term power purchase agreement
- Longi
- Los Angeles
- losses
- Low-carbon economy
- low-cost
- lowest bidders
- Low Tension
- LREDA
- Lubi Electronics Ahmadabad
- Lucknow
- Luoyang Suntech Power
- Lutyens' Bungalow Zone
- Lux Research
- LV/HV/EHV
- Lyndon Rive
- M. Deena Dayalan
- M/s. A.R. Solar Power. Dehradun
- M/s. Abans Commodities. Mumbai
- M/s. ACME Solar Holdings Pvt. Ltd. Gurgaon
- M/s. Adani Green Energy Ltd.. Ahemdabad
- M/s. Aditya Birla Nuvo Ltd.. Mumbai
- M/s. AMD Industries Ltd.. New Dehli
- M/s. Ashok Aneja. Rudrapur. New Delhi
- M/s. ASP & Co.. New Delhi
- M/s. Asun Solar & Co.. New Delhi
- M/s. AVI Enterprises. New Delhi
- M/s. Bansal Naturevest Ltd. Mumbai
- M/s. Composite Engineers. Dehradun
- M/s. Continental Engines Pvt. Ltd.. Gurgaon
- M/s. DDF Consultant Pvt. Ltd. New Delhi
- M/s.Dev International
- M/s.Dynamize Solar (P) Limited
- M/s. Eastman International. Ludhiyana
- M/s. Emami Power Ltd.. Kolkata
- M/s.G.R.T. Silverwares
- M/s.G.R.Thangamaligai & Sons
- M/s.G.R.Thanga Maligai (Firm)
- M/s. Gaurav Arora. Rudrapur. US Nagar
- M/s. Global Coal & Mining Pvt. Ld.
- M/s. Global Coal & Mining Pvt. Ld. Gurgaon
- M/s. Goyal Glass Ware Pvt. Ltd. AGRA
- M/s. Hydro Power Engineers. Dehradun
- M/s. Impex India. Kolkata
- M/s. JLTM Energy India Pvt. Ltd.. Varanasi. U.P.
- M/s. Madhav Infra Project Ltd.. Vadodra
- M/s. Makin Developers Pvt. Ltd. Panipat. Haryana
- M/s. Mokia Green Energy Pvt. Ltd.. New Delhi
- M/s.Narbheram Vishram
- M/s. Nilah Energy Pvt. Ltd.. Chennai
- M/s. NLC India Limited
- M/s. NP Agro (India) Industries Ltd.. Bariely
- M/s.NVR Energy Private Limited
- M/s. Omkar PowerTech India Pvt. Ltd.. Dehradun
- M/s. Pearl Green Energy Pvt. Ltd.. Mumbai
- M/s. Prabh Dayal Om Parkash Pvt. Ltd.. New Delhi
- M/s. Premier Plant Serices Pvt. Ltd.. Chandrapur
- M/s. Profigate Infra Gasoline. Roorkee
- M/s. Punj Llyod Infrastructure Ltd. Gurgaon
- M/s. Puran Chand. Rudrapur. US Nagar
- M/s. Purshotam Industries Ltd. New Delhi
- M/s.Raasi Green Earth Energy Pvt.Ltd.
- M/s. Ramesh Steels. Ludhiyana
- M/s.Rays Power Infra (P) Limited
- M/s. Rays Power Infra Pvt. Ltd.. Jaipur
- M/s. Redwoods Infrastructure Pvt. Ltd.. Banglore
- M/s.ReNew Solar Energy (Rajasthan) Private Ltd.
- M/s. RP Infrapower Pvt. Ltd.. Dehradun
- M/s.Sai Jyothi Infrastructure Ventures (P) Limited
- M/s. Sara Creation Inc.. New Delhi
- M/s. SGS Energy. New Delhi
- M/s.Shapoorji Pallonji Infrastructure Capital Company (P) Ltd.
- M/s. Shri Natraj Chemtech Pvt. Ltd.. Kanpur
- M/s.Solitaire BTN Solar Private Limited
- M/s. Sourabh Arora. Rudrapur. US Nagar
- M/s. Surana telecom & Power Ltd.. Secundrabad
- M/s. Synefra Engineering & Construction Co. Ltd
- M/s.Talettutayi Solar Project Two (P) Limited
- M/s. Torrent Energy Limited
- M/s.Udayasooriyan
- M/s. UJVN Ltd. Dehradun
- M/s. Vega Auto Accessories Pvt. Ltd.. U.S. Nagar
- M/s. Vimal Transformer Corporation. Moradabad
- M/s. Vishal Techno Commerce Ltd.. Mumbai
- M/s. Vivaan Solar Pvt. Ltd. Haridwar
- M/s Azure Power India Private
- M/s Bhadresh Trading
- M/s Dosti Realty Limited
- M/s Emami Power Limited
- M/s Gola Ganpati motors. Haldwani
- M/s Interocean Shipping India
- M/s Jubilant Infrastructure Pvt. Limited
- M/S Kankaria Group
- M/s K K Rao Engineering Works
- M/s NVR Solar Private Limited
- M/s Welspun Renewables Energy Private Ltd
- Macquarie
- Macquarie Group
- Made Easy Education Pvt. Ltd.
- Madhav Gadgil
- Madhav Infra Projects Ltd.
- Madhav lnfraprojects- Vadodara
- Madhya Gujarat Vij. Co. Ltd
- Madhya Pradesh
- Madhya Pradesh Electricity Regulatory Commission (Cogeneration and Generation of Electricity from Renewable Sources of Energy) (Revision-I) Regulations 2010
- Madhya Pradesh Electricity Regulatory Commission (MPERC)
- Madhya Pradesh Power Management Corporation Limited
- Madhya Pradesh Wind Tariff
- Madurai
- Madya Pradesh
- magazine
- magnesium chloride
- Magsaysay
- MahaGenco
- Maharashtra
- MAHARASHTRA ELECTRICITY DUTY ACT
- Maharashtra Electricity Regulatory Commission
- Maharashtra Energy Regulatory Commission
- maharashtra india
- Maharashtra Renewable
- Maharashtra Solar
- Maharashtra Solar Policy
- Maharashtra State Electricity Distribution Company Limited
- Maharashtra State Electricity Distribution Company Ltd
- Maharashtra State Load Dispatch Centre (MSLDC)
- Maharashtra State Power Generation Company Ltd
- Maharashtra Vij Grahak Sanghatana
- Maharshtra WInd Policy
- Mahavitaran
- Mahbubnagar
- Maheswari Mining & Energy Pvt Ltd
- Mahindra
- Mahindra & Mahindra
- Mahindra EPC (142 MW)
- Mahindra EPC Services Pvt. Ltd
- Mahindra EPC Services Pvt Ltd Mumbai
- Mahindra Group
- Mahindra Renewables
- Mahindra Renewables (Rs 4.68)
- MAHINDRA SURYAPRAKASH PRIVATE LIMITED
- mainland
- Malaysia
- Mali
- management salaries
- Managing Director
- mangalore india
- Manipur
- MANIREDA
- Manmohan Singh
- manufacturers
- Manufacturing
- Manufacturing-Linked-PPA
- manufacturing cost
- manufacturing sector
- Manu Karan
- map
- Map of India
- margazhi
- Maria
- Maria van der Hoeven
- Marine
- market
- Market capitalization
- market intelligence group
- market pricing on arms length basis
- Market share
- Masdar City
- Massachusetts Institute of Technology
- Material
- Materials science
- Mauna Loa
- maximum power output
- Maximum Power Point Tracker
- Mechanical engineering
- MEDA
- Medak
- Medha Energy Pvt Ltd
- medium power
- Medors Renewable Energy Pvt. Ltd.
- Mega Solar
- megawatt power plant
- megawatt project
- Megawatt Solutions
- Megha Engineering ft Infrastructures Ltd
- Meghalaya
- Meghalaya Policy
- Melbourne Convention and Exhibition Centre
- Member state of the European Union
- MEMC SunEdison
- Memorandum of understanding
- MERC
- MERC MYT Regulations 2011
- Mercom Capital
- Mercom Capital Group
- MERC RE Tariff Regulations
- metal fingers
- Methanol
- Methodology
- Mexico
- Meydbray
- Michael Adams
- Michael Liebreich
- Micro-Grid
- micro finance institutions
- Micro Grid
- Microgrids
- Microsol
- Middle East
- middle east asia
- migration scheme
- Miguel Nicolelis
- Mihri Ozkan
- mike ahearn
- Military Forces
- mined-out areas
- Mingyang
- Mini-grid
- mini-grids
- Mini/ Micro hydro projects
- Mini Grid
- Ministry Of Commerce
- Ministry of Defence
- Ministry of Economy
- Ministry of Environment and Forests (India)
- Ministry of Finance
- Ministry of New & Renewable Energy
- Ministry of New and Renewable Energy
- Ministry of New and Renewable Energy (India)
- Ministry of New and Renewable Energy (MNRE)
- Ministry of New and Renewable Energy Joint
- Ministry Of Statistics And Programme Implementation
- Mint
- Mission
- MIT
- mitigation option
- Mizoram
- mnre
- MNREDA
- MNRE Rural Access Programme
- MNRE secretary Anand Kumar
- Models
- Modernization
- Modern Solar
- Modern Solar Private Limited
- Modern Solar Pvt Ltd
- Modi
- Modular
- module
- module manufacturers
- Module mounting structures
- Mohan Energy Corporation Pvt Ltd
- Mohoba Solar (Rs 4.54)
- Mohr Davidow Ventures
- molecular alignment
- molybdenum disulfide
- Monday
- Montek Singh Ahluwalia
- Morocco
- Mortkasee
- MOSER BAER
- Moserbaer Clear Energy Ltd.
- Moser Baer Powergen Ltd
- Moser Baer Solar
- Moserbaer Solar
- Moti Nagar
- MoU
- MP
- MP 200MW
- MP Discom
- MPPMCL
- MP POWER MANAGEMENT COMPANY LIMITED
- MP Power Management Company Ltd.
- MPSEZ Utilities Pvt. Ltd
- MP Solar
- MPTRADECO
- MPUVNL
- MP Wind Policy
- MP Wind Tariff
- Mr. John Thomas
- Mr. Karan Goel
- M R Ramesh of Chikkaballapur
- Ms.. Gayatri Dilip Lalage
- Ms. RGS Solar Power Pvt. Ltd.. New Delhi
- Ms. World Wide Resorts Pvt. Ltd.. New Delhi
- MSECDL
- MSEDCL
- MSEDCL Net metering
- MSETCL
- MSLDC
- MSPGCL
- MSW
- MTRMR
- Multi-Year Tariff Petition
- Multijunction photovoltaic cell
- Mulund
- Mumbai
- Mumbai Net Metering
- Mundra Solar PV Limited
- Munich
- Municipal Solid Waste
- Must Run Status
- MW
- MWp
- MX Solar Power Limited
- Mycorrhizal
- MYT Control Period
- Mytra Energy
- Mytrah (350 MW)
- Mytrah Energy India Ltd
- Nabard
- Nagarjuna Sagar Dam
- Nalgonda
- Nallari Kiran Kumar Reddy
- Name of the Participant
- Nameplate capacity
- Namibia
- Nanosolar
- Nanostructures
- NAPCC
- Narayan Rane
- Narbheram Vishan
- Narbheram Vishan - Atha
- Narendra Kumar Khanna
- Narendra Modi
- NASDAQ
- natgrp
- Natham R Viswanathan
- National Aluminium Company Ltd.
- National Bank for Agriculture and Rural Development
- National Clean Energy and Environment Fund
- National Clean Energy Fund
- national electricity
- National Electricity Plan (NEP)
- national energy research
- National Housing Bank
- National Metrology Institute of Germany (Physikalisch-Technische Bundesanstalt – PTB)
- National Natural Science Foundation of China
- National Oceanic and Atmospheric Administration
- national renewable energy
- National Renewable Energy Laboratory
- national renewable energy laboratory nrel
- national resources defense council
- National Resources Defense Council (NRDC)
- national science foundation
- National Solar Energy Federation of India
- National Solar Mission
- National Tariff Policy
- National University of Singapore (NUS)
- National Bank
- Natiural gas
- Natural Gas
- Natural Group
- nature
- Nature Communications
- Nature Photonics
- Naturgy
- Navi Mumbai
- Navkar Export- Tirupur
- NayaRaipur
- NCEF
- NEDCAP
- NEDO
- Neel Metal Products Ltd.
- Negotiations
- Nelco Group
- Nepal
- net-zero
- Net Applicable Tariff Rate
- Net metering
- net worth
- Networth Projects Private Limited
- Nevada
- New & Renewable Energy Sources- Solar
- New capacity
- new Delhi
- new delhi india
- New Delhi Municipal Corporation
- New Energy and Industrial Technology Development Organization
- new farms
- NEW Grid
- New Hampshire
- New Jersey
- newport beach california
- new projects
- new renewables
- News
- New Technologies – Grid scale battery energy storage systems.
- New York
- New York City
- New York Stock Exchange
- New York Times
- Neyveli Lignite Corporation Limited
- Neyveli Lignite Corporation Ltd.
- NGDQs
- NHPC Limited
- Nicaragua
- nicobar
- Nicole Miller
- Niestetal
- Nigeria
- Nimoto Consulting Engineers Pvt Ltd
- Nirma
- Nirmala Sitharaman
- Nissan Leaf
- Nitin Gadkari
- Nitish Kumar
- nitrogen-doped graphene quantum dots
- nitrogen oxides
- NKDA
- NLC
- NOAA
- Noida
- Non-conventional Energy and Rural Technology (ANERT)
- Non-fossil fuel-based co-generation Plants
- Non-Fossil Fuel based Co-Generation Projects
- Non-fossil fuel based generation and Cogeneration projects
- non-lapsable
- non - solar rec
- non conventional energy resources
- Non Utility
- NO Removal
- norms
- north american international auto
- North Carolina State University
- Northern Power Distribution Company Limited of Telangana
- Northern Power Distribution Company of Telangana Limited
- North India
- Northwest
- Northwestern University
- Norway
- Novus Green Hyderabad
- NPDCL
- NPD Solarbuzz
- NRDC
- NREDCAP
- NREL
- NRSE
- NSEFI
- NSM
- Nth Power
- NTP
- NTPC
- NTPC Limited
- NTPC Ltd.
- Nuclear
- Nuclear decommissioning
- nuclear energy
- nuclear energy report
- Nuclear Hazard
- Nuclear hydrogen
- Nuclear Plant Risk
- Nuclear Power
- Nuclear Power Corporation of India
- Nuclear Power Issues
- Nuclear Power Plant
- nuclear power plants
- Nuclear Risks
- Nuclear Safety
- nuclear weaponisation
- number of states
- Numerical control
- NV Energy
- NVR INFRASTRUCTURE AND SERVICES PRIVATE LIMITED
- NVR Renew Private Limited
- NVR Vidyut Pvt. Ltd. - Kolkata
- NVVN
- NVVN FRAUD
- NV Vogt Energy (India) Pvt Ltd
- NYSE
- O&M
- Oakbridge Energy Private Limited
- Obama
- Ocean Renewable Power Company
- Odisha
- Odisha announces solar energy project
- Odisha electricity regulatory commission
- Odisha government
- Odisha invites bids for 25MW solar project
- Odisha Renewable Energy Development Agency
- Odisha solar power project
- OECD
- OERC
- Off-grid
- Off-grid subsidy
- off grid Solar
- Offgrid solar
- offgrid solar power
- Office of Naval Research
- Office of the United States Trade Representative
- Offshore Wind
- offshore wind energy
- Offshore wind power
- Oil
- oil industry
- oil shale
- oil sludge
- Olympus Capital
- Oman
- OMC
- On-grid
- OnPoint Technologies
- onshore wind turbines
- Ontario
- Oommen Chandy
- Open Access
- operational endeavors
- OPERATION AND MAINTENANCE
- Operations and Maintenance
- OPG POWER GENERATION PRIVATE LIMITED
- opposition leader
- optical transparency
- Optimal generation capacity mix
- Orange Renewable Power Private Limited
- Orchha
- OREDA
- organic photovoltaic cell
- Organic Solar
- Organic solar cell
- organic solar cells
- Organisation for Economic Co-operation and Development
- Oriental Sales Agenices India Pvt. Ltd.
- Orient Green Power
- Orissa
- Orissa Renewable Energy Development Agency
- Ostro Energy
- Others
- outdated facts
- Outlook
- Overloading
- oxygen
- P50
- P90
- Pacific Northwest National Laboratory
- PAE Renewables Mumbai
- Pakistan
- Palimarwar Solar Project Pvt. Ltd.
- Pali Rajasthan
- Panasonic
- Panasonic solar cell
- Panasonic solar cell efficiency
- Panasonic solar cell efficiency record
- Panasonic solar efficiency
- Pandian
- Panel Defects
- Panel Failure
- Panel Manufacturer
- Par
- parabolic troughs
- Paraguay
- Paramakudi
- Para Military
- Para Military Forces
- Parampujya Solar Energy Pvt Ltd
- parity
- Particulate Matter
- Particulates
- Paschim Gujarat Vij Co. Ltd
- Pashupathy Gopalan
- PashupathyGopalan
- Patna
- Patuli
- Pawan Kaushal
- PCIL Pune
- peak evening hours
- peak hours
- peak periods
- peak power demand
- peak power output
- PEC
- PEDA
- PEIL
- Pellet fuel
- penalty
- Penang
- percentage distributions
- performance guarantee
- performance guarantees
- performance ratios
- Perlight Solar
- PERMITS
- Perrysburg Ohio
- persistent myths
- personal staff
- Peru
- PES Engineers Pvt Ltd
- Peter Droege
- Peter Huang
- Peter Thiel
- Petition
- Petroleum
- Petrolium
- Petronet
- Petronet LNG
- Pew Charitable Trusts
- Phalodi
- Phase-II Batch-II Tranche-I
- Phase 1
- phase1 batch1
- Phase 1 Batch 1
- Phase 1 Projects
- phase ii
- phd chamber
- Phelan Energy Group
- phenomenon
- Philadelphia
- Philippines
- photocurrent
- photoelectrolysis
- photon
- Photon Energy System Ltd
- Photon Energy Systems
- Photon Energy Systems Ltd
- photonix
- photophysics
- photovaltaic
- Photovolta
- Photovoltaic
- PHOTOVOLTAIC(PV) PROJECT DEVELOPMENT
- Photovoltaic Cells
- photovoltaic energy
- photovoltaic group
- photovoltaic performance
- photovoltaic plant
- photovoltaic power plant
- photovoltaic power system
- photovoltaic power systems
- Photovoltaics
- photovoltaics industry
- Photovoltaic system
- photovoltaic systems
- PI Berlin
- Pinak Power Associates (Opc) Pvt. Ltd.
- Pious Solar Energy Pvt Ltd
- Pisci-Culture
- Piyus Goyal
- Piyush Goyal
- PJM Interconnection
- P K Sinha
- planet
- Planning commission
- plantations
- PLANT DESIGN
- plants
- plant solutions
- Plexus Infratech Private Limited
- PLF Solar
- PLG Power
- Plug-in hybrid
- PM 2.5
- PMP Auto Components Pvt Ltd.
- POKARAN SOLAIRE ENERGY PRIVATE LIMITED
- Pokhran
- Poland
- polar ice caps
- Poles
- POLICIES AND SUPPORT MECHANISMS FOR SOLAR PV
- Policiesin
- policy
- policy assumptions
- policy draft
- policy makers
- policymakers
- political clout
- political futures
- politics
- Politics of Germany
- polluters
- Pollution
- Pollution Norms
- Polycrystalline silicon
- Polymer solar cell
- polysilicon manufacturers
- polysilicon prices
- polysilicon producers
- positive reply
- potential bidders
- potential induced degradation
- Pothan
- Power
- power auction
- Power Banking
- Power Battery
- power block
- Power Bundling
- power capacity
- power companies
- power conversion efficiency
- Power Corporation of Canada
- power crisis
- Power Cuts
- power demand
- Power density
- power distribution companies
- power distribution firms
- power distribution sector
- Power engineering
- Power Exchange
- Power Exchange India
- power feeders
- power finance corporation
- powerful
- power gap
- power generation
- power generation capacity
- Power Generation In India
- power generation plant
- power generation plants
- power grid
- Power Hikes
- powerhouse
- power industry
- power interruptions
- Power Losses
- power management company
- Power Minister
- Power MInistry
- PowerMonitor
- Power One Micro Bangalore
- Power One Micro Systems Pvt Ltd
- Power outage
- Power Plant
- Power Plant Commissioning
- power plants
- Power podcast
- power portal
- power prices
- power producer
- power producers
- Power Projects
- power purchase
- Power Purchase Agreement
- Power purchase agreements
- Power Purchase Agreements (PPAs)
- power restrictions
- Power Revision
- power sector in india
- power sectors
- power shortage
- Power Solutions
- Power station
- Power Storage
- Power Supply
- Power Supply Agreements (PSAs).
- Power Supply Termination
- power system
- power tariff
- Powertech Engineers
- power trading
- powertrain
- Powerwall
- PPA
- PPAs
- PPP
- PPS Enviro Hyderabad
- Prabhadeep Industries
- prakash gupta
- Prakash Industries Ltd.
- Pramod Deo
- pranav gupta
- Pranav Mehta
- Pranav R Mehta
- Prasaran Nigam
- Praveen Mahajan
- Praveer Sinha
- PRAYATNA DEVELOPERS PRIVATE LIMITED
- PR Director
- Premian Investments Pvt Ltd
- Premier Solar Systems
- presidency
- Price
- Price level
- princeton professor
- princeton researchers
- Principal Regulations
- principal repayments
- Prius
- private coal producers
- private developers
- private equity
- Private sector
- private sector firms
- private sector participation
- Privatisation
- Privatization
- procedural hurdles
- Procurement
- procurement platform
- procurement price
- product
- production target
- production tax credit
- Prof. Peter Bäuerle
- Professor
- Professors in the United States
- profitable strategies
- Project
- project developers
- Project management
- Projects
- Projects MW
- propulsion concept
- propulsion technology
- prospective bidders
- prospective developer
- prospective investors
- provisional duties
- Prysmian Group announces the successful commissioning of the inter-array cable system for the Fécamp offshore wind farm
- PSA
- PSERC
- PSPCL
- PSU
- PSUs & their subsidiaries
- PTC
- public enemy number
- public private partnership
- Public Private Partnership (PPP) Status
- Public Sector Banks
- Public Sector Undertakings
- Public Sector Units
- public sentiment
- Public utilities commission
- Puducherry
- Pulickel Ajayan
- Pulse Power Kolkata
- P Uma Shankar
- Punam Energy Pvt Ltd
- Pune
- punitive tariffs
- Punjab
- Punjab (Govt. of Punjab)
- Punjab Government
- Punjab NetMetering
- Punjab Pakistan
- Punjab RE Tariff 2015-16
- Punjab Solar
- Punjab Solar Policy
- Punjab Solar RfP
- Punjab State Electricity Regulatory Commission
- Punj Lloyd
- Punj Lloyd Infrastructure Limited
- purchase obligation
- Purchasing power
- purchasing power parity
- Purdue University
- Purshottam Profiles Pvt. Ltd.
- Purti Group
- Purti Solar Systems
- pushing the government to increase the PLI amount by an additional Rs19
- PV
- pv array
- PV Cells
- pv complex
- PV Contracts
- pv demonstration
- PV Design
- PV EPC
- PV Evolution Labs
- PV Grid Plants
- pv industry
- PV installations
- PV Manufacturer
- pv market
- pv module
- PV Module AUdit
- PV module designers
- PV Modules
- PV Panels
- PV Panesl
- PV Plants
- PV Power
- PV power source
- pv products
- PV Project
- pv projects
- PVR Projects Ltd
- PV Storage
- PVSyst
- pv system
- PV System Integrator
- Pvt. Initiative (Roof top) MW
- pv tech
- pv technologies
- PV Wafers
- PXI
- Pyrococcus furiosus
- Qatar
- Quality
- Quality Control Order and guidelines of the Ministry of New and Renewable Energy (MNRE)
- quantum dots
- quantum efficiency
- quarterly status
- quasi-random
- Raajratna Energy Holdings Private Limited
- Raajratna Energy Holdings Pvt Lts
- Raasi Green Earth Energy
- Rachamallu Forgings Pvt Ltd
- Radiant Solar Hyderabad
- radiation basics
- radiation resource
- radio-frequency identification (RFID) tag
- RAGA RENEWABLE ENERGY PRIVATE LIMITED
- Raghu Infra Pvt Ltd
- Rahul Sankhe
- Railways
- Rain Cements Limited
- Raipur
- Rajarhat-New Town
- Rajasthan
- Rajasthan (Govt. of Rajasthan)
- Rajasthan Electricity Regulatory Commission
- Rajasthan Electronics & Instrumentation Limited
- Rajasthan Electronics & Instruments Ltd.
- Rajasthan government
- Rajasthan high court
- Rajasthan Renewable Energy Corporation Limited
- Rajasthan Renewable Energy Corporation Limited (RRECL)
- Rajasthan Solar
- Rajasthan Solar Association
- Rajasthan solar programme
- Rajathan
- Rajendra Nimje
- Rajeshwar Rajpurohit
- rajiv gandhi
- Rajkot
- Raj Prabhu
- Rajya Sabha
- rajya sabha member
- Rama
- Ramana Rao
- Ramanthapuram
- ramon magsaysay award
- Ranga Reddy
- range grid
- Rangsdorf
- Ranji Solar Energy Pvt Ltd
- ransmission and distribution losses
- Rattan India Solar 3 Limited
- Ratul Puri
- Ravano Solar India Pvt Ltd
- Ravano Solar India Pvt Ltd Bangalore
- Ravi Khanna
- Ravindra Energy Limited
- Raydeon Energy Private Limited
- Ray Kurzweil
- Ray Noble
- Rays Power Experts Design Co.
- Rays Power Experts Pvt Ltd
- Rays Power Infra Pvt Ltd New Delhi
- RBC Capital Markets
- RBI
- RDA Energy Pvt. Ltd
- RDF
- RE
- real data
- REC
- REC 2nd Amendment
- RE capacity
- REC Extension Hearing
- Rechargeable battery
- REC Mandatory
- REC mechanism
- Record Organic Efficiency
- REC Projects
- REC Purchase India
- REC Scheme MW
- REC Solar
- Recurrent Energy
- Recycle
- recycled
- Recycling
- Reductionsin
- Refex
- Refex Energy
- Refex Energy (Rajasthan) Pvt. Ltd.
- Regulation
- Regulations
- regulatory commission
- REIL
- Rejuvenating
- reliability
- reliability index
- Reliance ENergy
- Reliance Industries
- Reliance Industries Ltd.
- Reliance Infra
- Reliance Infrastructure
- Reliance Power
- Reliance Power (400 MW)
- Reliance Sasan UMPP
- Reliance Solar
- Relyon Solar Pvt Ltd
- REN21
- Reneging
- Rene Moerman
- ReneSola
- Renesolar Jiangsu
- Renew
- Renewable
- renewable blog
- Renewable Electricity
- Renewable Energy
- Renewable Energy Act
- Renewable Energy Act India 2015
- Renewable Energy and Cleantech Forum - India
- renewable energy and mines minister Piyush Goyal
- renewable energy blog
- renewable energy business
- Renewable Energy Certifcates
- Renewable Energy Certificate
- Renewable Energy Certificate for Renewable Energy Generation
- Renewable Energy Certificate Mechanism
- Renewable Energy Certificates
- Renewable Energy Certificate System
- Renewable energy commercialization
- renewable energy companies
- renewable energy company
- Renewable Energy Corporation
- renewable energy development
- Renewable Energy Development Agency
- Renewable Energy Development Corporation
- Renewable Energy Event
- renewable energy finance forum
- renewable energy generation
- renewable energy generator
- renewable energy india
- renewable energy industry
- renewable energy installations
- Renewable energy in the United States
- renewable energy laboratory
- renewable energy magazine
- RenewableEnergyMagazine.com
- renewable energy market
- renewable energy markets
- renewable energy metering
- renewable energy plants
- renewable energy policy
- Renewable Energy policy 2015
- renewable energy products
- Renewable Energy Programme
- renewable energy project
- renewable energy projects
- renewable energy resources
- renewable energy sector
- renewable energy source
- renewable energy sources
- renewable energy systems
- Renewable Energy Tariff
- renewable energy technologies
- Renewable Jobs
- Renewable Markets India
- Renewable Power
- Renewable Power Plants
- renewable power sources
- Renewable Purchase Obligation
- renewable purchase obligation (RPO)
- Renewable Purchase Obligations
- Renewable Report 2016
- Renewables
- Renewables 2016
- Renewables 2021
- Renewables Global Status Report
- renewable sources of energy
- renewable technology
- Renew Power
- Renew Power (400 MW)
- Renew Solar Energy Pvt Ltd
- Renew Solar Power- Gurgaon
- ReNew Solar Power Private Limited
- Renew Solar Power Pvt. Ltd.
- Renew Solar Pwer Ltd. Gurgaon
- RenewSys
- Renovables
- RE Plants
- Report
- RE Power
- Repowering
- Request for proposal
- RERC
- RESCO
- research
- Research and development
- research thrust areas
- Reserve Bank of India
- residential
- Residential PV
- Residential Solar
- Resilience
- resolution equipment
- Resource Future
- resource maps
- resource scarcity
- Restructuring
- retail electricity
- retaliatory measures
- RE Tariff Regulations
- Reuters
- Reva
- Revenue
- revenue register
- Revenue Secretary Hasmukh Adhia
- Reverse Auction
- Reverse Bidding
- Revised Draft Guidelines
- Rewa
- Rewa Solar Park
- RFE
- RFP document
- Rfrex Mumbai
- Richard Kaner
- Richard Soderberg
- Rick Luebbe
- Right to Information Act
- Right to Information Act 2005
- Rishabh Buildwell Pvt. Ltd.
- Rising Sun Energy Pvt Ltd
- Risk
- Rita Pandey - environmental economist and professor at the National Institute of Public Finance and Policy in New Delhi
- RiTCOE
- Ritesh
- Ritesh Pothan
- Riverside’s Bourns College of Engineering
- Rk Tech (India) Pvt Ltd
- Rmb Power Projects Private Limited
- Road
- Robert Bosch GmbH
- Robert R. McCormick School of Engineering and Applied Science
- robust capacity
- Rocky Mountain Institute
- Roha Dyechem Private Limited
- Ron Kirk
- Rooftop
- rooftop power
- Rooftop PV
- ROOFTOP PV & SMALL SOLAR POWER GENERATION PROGRAMME (RPSSGP)
- Rooftops
- Rooftop Solar
- Rooftop Solar Policy
- Rooftop Solar Systems
- Rooftop Subsidy
- rooftop systems
- RPO
- RPO MW
- RPO Penalty
- RPSSGP
- rrec
- RRECL
- Rs. 2.44 KWh
- Rs 2.44 per unit
- Rs 2.44/unit
- Rs 3.3 per unit
- Rs 3.15 per unit
- r shankar
- RTI Act
- RTI International
- rtionline.gov.in
- RTPV
- Ruchin Gupta
- Rural area
- Rural Electricity
- rural electrification
- Rural Lighting
- Rural Solar Micro Grid
- Russia
- RWE
- RWE secures 684-megawatt project together with Mitsui and Osaka Gas in Japanese offshore wind energy auction
- S
- S.K.Goel
- sabha constituency
- Sacramento California
- Sacramento Municipal Utility District
- Safeguard Duties
- Safeguard Duty
- safety mechanisms
- saga series
- SAG Solarstrom
- Sahiwal District
- SAIC Motor
- Sai Jyothi Infrastructure Ventures Private Ltd.
- SAI MATHILI POWER COMPANY PRIVATE LIMITED
- Sai Sudheer
- SAISUDHIR ENERGY LIMITED
- Salient Features State Solar Policy
- Sally Benson
- Salt
- Sam Wilkinson
- San Antonio
- Sandia National Laboratories
- San Diego Unified School District
- San Francisco
- Santa Fe Institute
- Sapec Enviro
- Saranya Electronics Pvt Ltd
- Sargam Retails PVt. Ltd.
- Sarita Vihar
- Saritha
- Satec Envir Engineering (I) Pvt Ltd
- Satoru Kuriyagawa Chief Technology Officer
- Saturday
- Saudi Arabia
- Saurabh Patel
- Saving
- sawmill residues
- SBG Cleantech
- Scailex Corporation
- Scam
- Schedule Charges
- Scheduled Power
- scheduling
- science
- Scott Brusaw
- Scottish government
- Scripps Institution of Oceanography
- SDSL Electronics Private Limited
- sea salt
- SECI
- secretary
- Secretary-General of the United Nations
- Secretary at India’s Ministry of New and Renewable Energy (MNRE)
- Section 80 IA
- sector
- Segregation
- SEI
- SEIA
- SEI Arushi Private Limited
- SEI Green Flash Private Limited
- SEI Green Flash Pvt Ltd
- SEI L'Volta Pvt Ltd
- SEI Peoples Pvt Ltd
- SEI Phoebus Private Limited
- SEI Sitara Pvt Ltd
- SEI SOLAR POWER PRIVATE LIMITED
- SEI Suncells Pvt Ltd
- SEI Surya Lab Pvt Ltd
- SEI Tejas Pvt Ltd
- Sekema Power Generation Pvt. Ltd.- Indore
- SELCO
- Selco India
- Self Certification
- self consumption
- semi conductor
- semiconductor
- semiconductor crystals
- semiconductor substrates
- semi –processed solar PV cells
- Semprius
- SERC
- serial entrepreneur
- SERIIUS
- Service Tax
- Servomax Hyderabad
- settlement option
- Sevenn Rays Energy Private Limited
- Severe Weather
- SGD
- SHAKTI BHAWAN
- Shakti Trans Infra
- Shale
- Shale Gas
- Sham 1
- Shams solar power station
- Shanghai JA Solar Technology
- Shanghai Jinglong Solar Energy Technology
- Shan Solar
- Shapoorji Pallonji (150 MW)
- Shapoorji Pallonji Energy Gujarat Private Limited
- Shapoorji Pallonji Infrastructure Capital Company Ltd
- Shapoorji Pallonji Solar PV Pvt. Ltd
- Shapporjee Paloonjee-Mumbai
- Sharad Mohanka
- Sharda Construction And
- Sharda Construction and Corporation Private Ltd
- Shares
- Sharika Enterprises
- Sharika Enterprises Pvt Ltd
- Sharp
- Sharp Corporation
- Sharp Solar
- sheep breeder
- sheep farming
- Sheila Dikshit
- Sheldon Kimber
- Shi. Punit Goel
- Shivanand Nimbargi
- Shivanna Gowda R Patil of Bagalkot
- Shockley–Queisser limit
- shortage
- short term loans
- Shree Ganesh Jewellery
- SHREE SAIBABA GREEN POWER PRIVATE LIMITED
- Shri. A.K.Govil
- Shri. Abhijeet Ramesh Hinge
- Shri. Abhijit Sharma
- Shri. Anoop Kumar Gupta
- Shri. Ashish Kumar
- Shri. Bhupinder Pal Singh Gill
- Shri. Dharmesh Rajnikat Shah
- Shri. Dinesh Maheshwari
- Shri. G.K. Garuda Prasad
- Shri. Indra Prakash
- Shri. K.K.S. Gautam
- Shri. Ketan Jasani
- Shri. Kuman R. Siddhapura
- Shri. Lokendra Yadav
- Shri. Lovkesh Goel
- Shri. Mahendra Kumar
- Shri. Manoj Kumar Gupta
- Shri. Mukesh Jain
- Shri. Mukesh Sharma
- Shri. Naveen Arora
- Shri . Prakash B Nayak
- Shri. R. Arunkumar
- Shri. R.K. Khera
- Shri. Rajesh Kumar
- Shri. Ravindra Tiwari
- Shri. Rohtash Kumar
- Shri. S.V. Manohar
- Shri. Sanjay Deshpande
- Shri. Saurabh Kumar
- Shri. Sparsh Bali
- Shri. Surinder Kumar Kansal
- Shri. Thota Narayana Rao
- Shri. Vivek Soni
- Shri A.K. Singhal
- Shri A.S. Bakshi
- Shri Bhavesh Kumar V Doaria
- Shri Colonizers & Developers Pvt. Ltd.
- Shri Gireesh B. Pradhan
- Shri Hemant Sharma
- Shri Lalit Kaushik
- Shri M. Deena Dayalan
- Shri S.R Prabhu
- Shri Shakti Alternative Energy Ltd
- Shri Shashi Shekhar Giri
- Shri Sher Singh
- Shri Supinder Jeet Singh
- Shri Umesh Johar
- Shri Umesh Kant
- Shri V.K. Wadhwan
- shunt hot spots
- Shurjo
- shyam mehta
- Sidarrtha Energy Pvt Ltd
- Siddharth Malik
- Sikkim
- silicon dioxide
- Silicon Pv
- silicon solar cells
- Silicon Valley
- silicon valley toxics
- Silicon Valley Toxics Coalition
- silver paste
- Simplex Infra
- Simplex Infrastructures Limited
- Singapore
- Singareni
- Single Axis Tracking Technology
- Single Line Diagram (SLD)
- singlet exciton
- singlet fission
- SITE SELECTION
- Sitraruvipatti
- Skylark Industries
- Sky Power (200 MW)
- Sky Power South East Asia Holding Ltd
- SLDC
- SLG Solar Systems
- SMA
- SMA Inverter
- Small hydro
- Small Hydro Policy
- Small Hydro Power
- Small Hydro Power Projects
- Small Hydro Projects
- SmartCalc
- Smart Energy
- Smart Roof Solar Solutions Pvt Ltd
- SMA Solar
- SMA Solar Technology
- Smog
- snail tracks
- Snohomish County Public Utility District
- Soalr India
- Soalr PV
- Soalr wind
- Social system
- Socrates
- sodium chloride
- soft shading
- software
- soil conditioner
- Soitec
- sola Cooling
- solae water heaters
- Solairedirect
- Solairedirect Energy- Pune
- Solairedirect Energy India Pvt. Ltd.
- sola modules
- Solana
- Solana Generating Station
- Solar
- Solar-powered
- Solar 1000MWp
- Solar Achievements
- solar africa
- solar ag
- Solar albania
- Solar Anti-dumping
- Solar Anti Dumping Duty
- Solar auction
- Solar Backsheet
- Solar Bankability
- Solar Banking
- solar barbuda
- solar bidding
- Solar Bids
- Solar Bids TN
- Solar Biomass Hybrid
- solar blog
- solar blog india
- Solar BOOT
- Solar Boot India
- Solar BOOT Model India
- Solar BOS
- SolarBridge Technologies
- Solar Bundling
- solar business
- solar businesses
- solarbuzz
- solar capacity
- Solar Captive
- Solar Carbon Cell
- solar cars
- Solar Cell
- Solar Cell Efficiencies
- solar cell efficiency
- solar cell product
- solar cell production
- Solar cells
- solar cell technology
- Solar Certifications
- solar chaina
- Solar China
- Solar Cities
- SolarCity
- Solar Cleaning
- solar club
- Solar Cold Storage
- solar Colombia
- solar commissioning certificate
- solar companies
- Solar Comparison
- Solar Conference
- solar construction
- Solar cooker
- Solar Cookers
- Solar Cooling
- solar could
- Solar CSP
- Solar Curve
- Solar Customs Duty
- Solar Defects
- solar deployment
- Solar developed
- Solar Developer
- Solar Developers
- Solar Development
- solar developments
- Solar Digita
- Solar DNI
- Solar Efficiency
- solar electricity
- Solar Embedded Roads
- solar energy
- Solar Energy Association of Gujarat
- solar energy conversion
- Solar Energy Cor
- Solar Energy Corp. of India Ltd (SECI)
- Solar Energy Corporation
- SOLAR ENERGY CORPORATION OF INDIA
- Solar Energy Corporation of India (SECI)
- Solar Energy Corporation of India Limited
- Solar Energy Corporation of India Ltd (SECI)
- solar energy division
- solar energy generation
- solar energy india
- solar energy industries
- Solar Energy Industries Association
- solar energy industry
- Solar energy movement in India
- solar energy panels
- Solar Energy Professionals
- solar energy research
- Solar Energy Research Institute for India and the United States (SERIIUS)
- Solar Energy Research Institute of Singapore
- Solar Energy Society
- Solar Energy Society of India[SESI]
- solar energy storage
- solar energy systems
- solar energy technology
- solar eneygy
- Solar EPC
- Solar EPC India
- solar equipment imports
- solar europe
- SolarEVN
- solar exemptions
- solar expansion
- solar farm
- Solar Farmer PPA
- solar farms
- SOLARFIELD ENERGY TWO PRIVATE LIMITED
- solar fields
- solar films
- Solar Finance
- Solar FIT
- Solar Flight
- Solar Floating
- Solar Fridge
- Solar Frontier
- Solar Generation
- solar generation ration
- solar generators
- solargis
- Solar Glass
- solar government
- solarGovernment
- solar green energy
- Solar Grid
- Solar Grid Connected
- solar growth
- Solar GSt
- Solar Guide
- Solar Guidelines
- Solar Hearing
- Solar Heating
- Solar home
- solar hot water heating
- solar hybrid
- solar hydro
- solar hydrogen
- solar Hydropower
- solar import
- Solar Imports
- Solar Impulse
- solar incentives
- Solar India
- Solar India 2012-2013
- Solar India Blog
- Solar India PV
- Solar India Subsidy
- solar industry
- solar infrastructure
- Solar in India
- solar insolation
- Solar Installations
- Solar Installers
- Solar Institute
- Solar Integrated Technologies
- Solar Inverter
- Solar Inverters
- Solar Inverters Excise Duty Exemption
- solar investment
- Solar Investor
- Solar Irrigation
- solar Japan
- Solar Junction
- Solar Kerala
- solar kits
- Solar Lantern
- Solar Lanterns
- Solar Lebanon
- Solar Lighting
- Solar Loans
- Solar Manufacturers
- Solar Manufacturing
- Solar Map
- Solar Map India
- Solar Maps
- Solar Market
- solar markets
- Solar Markets India
- Solar Media
- Solar Mega PLants
- Solar Mega Power
- Solar Mega Projects
- Solar Mfg
- Solar Microgrid
- Solar Minigrid
- Solar Mission
- Solar Mobility
- solar modalities
- solar model
- Solar Module
- Solar Modules
- Solar Modules GST
- Solar Mounting Structure
- Solar myanmar
- solar net metering
- Solar O&M
- solar obligation
- solar off-grid
- Solar Off Grid Report
- solar oil
- Solar Open Access
- solar opportunity
- solar ower
- Solar Panel
- Solar Panel Customs Duty Exemption
- Solar Panel Defects
- solar panel manufacturers
- solar panel prices
- Solar Panel Recycling
- Solar Panels
- Solar Panel Structures
- solar parameters
- Solar Park
- Solar Park Implementation Agency (SPIA)
- Solar Parks
- Solar Park Subsidy
- Solar Penalty
- solar photovoltaic
- Solar Photo voltaic (PV)
- Solar Photovoltaic (PV)
- solar photovoltaic cells
- solar photovoltaic panels
- solar photovoltaic power
- solar photovoltaic project
- Solar photovoltaic PV
- Solar Photovoltaics
- Solar Photovoltaics/Systems/Devices/Components Goods (Requirements for Compulsory Registration) Order
- solar photovoltaic systems
- solar photovoltaic water pumping systems
- Solar Plane
- solar plans
- solar plant
- solar plants
- Solarplus Energy Pvt Ltd
- Solar policies
- Solar Policy
- Solar Policy India
- Solar Powe
- Solar Power
- Solar Power Developer
- Solar Powered Rickshaw
- Solar Power Energy
- solar power equipment
- solar power generation
- solar power generator
- solar power generators
- Solar Power India
- Solar Power International
- Solar Power Monitoring Stations
- Solar Power Packs
- Solar Power Pants
- solar power plant
- solar power plants
- Solar Power Plants India
- Solar Power Plnts
- Solar Power POlicy
- Solar Power Project
- Solar Power Project Developers
- solar power projects
- Solar Power RPO
- solar power station
- solar power systems
- solar power tariff
- solar power technologies
- Solar power tower
- solar power units
- Solar PPA
- Solar Prediction
- Solar Presentation
- solar prices
- solar procedures
- solar process
- solar production
- solar project
- Solar projects
- Solar Projects India
- Solar Prospects
- Solar Pumps
- solar Punjab
- Solar Purchase Obligations
- Solar PV
- SolarPV
- solar PV and flexibility resources to minimise overall system costs under given cost and performance assumptions. The results show that different mixes of flexibility resources – including grids
- Solar PV Cell
- solar PV cells
- Solar PV Cleaning
- Solar Pv Components
- Solar PV Defect
- Solar PV Defects
- solar PV deployment
- Solar PV Design
- Solar PV India
- Solar PV Jobs
- solar PV module
- solar pv modules
- Solar PV Panels
- Solar PV Plants
- solar PV power
- Solar PV Power Plants
- Solar PV Power Project Developers
- Solar PV Prediction
- Solar PV Projects
- Solar PV Pumps
- Solar PV rooftop
- Solar PV Rooftops
- Solar PV Standard
- Solar PV Storage
- solar pv systems
- SOLAR PV TECHNOLOGY
- Solar Quality
- Solar Quality Issues
- Solar R&D
- Solar Radiation
- solar radiation data
- Solar Radiation monitoring centers
- Solar Radiation Resource Assessment
- solar rec
- Solar REC Floor price
- Solar REC Forbearance price
- SOLAR Records
- SolarReEDS
- solar regulations
- solar renewable energy
- Solar Renewable Energy Certificate
- Solar Report
- solar requirement
- solar research
- SolarReserve
- Solar Residential
- Solar RFP
- Solar Rickshaw
- Solar Roads
- Solar Roadway
- Solar Robotic Cleaning System
- Solar Roof
- Solar Roofs
- Solar Rooftop
- Solar Rooftop Investment
- Solar Rooftop Power Plants
- Solar Rooftop Projects – Gross/Net Metering
- Solar rooftops
- solar rooftop systems
- solar rose
- Solar RPO
- Solar Scam
- solar secter
- solar sector
- Solar Semiconductor
- Solar SEZ
- solar Singapore
- Solar Solutions
- solar Spanish
- solar state
- Solar States
- Solar Stations India
- Solar Steam
- Solar Storage
- solar street lighting
- Solarstrom
- Solar Structures
- Solar Subsidy
- Solar Summit India
- Solar supply
- solar system
- solar systems
- Solar System with Battery
- Solar Tariff
- solar taxes
- Solar Tech India Presentation
- solar technology
- Solar Tender
- solar Thailand
- Solar Thermal
- Solar Thermal Design
- Solar thermal energy
- Solar Thermal India
- solar thermal plant
- Solar Thermal Power Projects
- Solar thermal projects
- solar thermal sector
- solar thermophotovoltaic
- Solar Third Party Connectivity
- Solartown Energy Solutions Pvt Ltd
- solar tracking system
- Solar Turkey
- Solar USA
- solar Vietnam
- Solar Village
- solar wafer
- solar Waste
- solar waste energy
- Solar Water Heater
- solar water heaters
- solar water heating
- solar water heating systems
- Solar Water Pumps
- Solar Wind
- SolarWorld
- Solarworld Energy Solutions Private Limited
- solat Thailand
- SolerCool
- solicitation
- Solid Solar
- Solid Waste
- solid waste disposal
- solid waste management
- Solitaire Powertech Pvt Ltd
- Solyndra
- sops
- South Africa
- south asian nation
- Southeast European Cooperative Initiative
- Southern Europe
- southern german state
- southern grid
- Southern Power Distribution Company of A.P. Ltd.
- Southern Power Distribution Company of Telangana Limited
- southern states
- South Korea
- south zone
- Sova Power
- Soy
- spain
- Spanish wind major
- Span Pumps Pvt Ltd
- SPD
- SPD/EPC Contractor
- SPDCL
- Speaker
- Spectrolab
- spin property
- SPML Infra Ltd
- SPO
- SPV
- SPV GmbH
- SPV Systems
- SPV water pumping
- SR Corporate Consultant Pvt Ltd
- Sree Nandhees Technologies Pvt Ltd
- Sree Nandhees Technologies Pvt Ltd Chennai
- Sri Avantika Contractors (I) Limited
- Srikakulam
- Sri Maruthi PowerGen India Private Limited
- SRK Solenergi Private Limited
- SRRA
- SSNR Power Private Limited
- Stacked
- stakeholders
- standardisation committees
- St Andrews University
- Stanford
- stanford graduate school
- stanford graduate student
- Stanford University
- stanford university scientists
- Star Energy Systems
- Statcom Noida
- Statcon Energiaa Pvt Ltd
- State-run power producer
- State/UT
- state advisory committee
- state electricity boards
- State electricity regulator
- State Electricity Regulatory Commission
- State Feed In Tariff
- state government
- state government policies
- state load dispatch center
- State of Goa
- State Policy
- State Policy MW
- States and territories of India
- states in india
- State Solar Policy
- state subsidy
- States with Solar in India
- Static Convertors (UPS)
- steam boilers
- steam power plant
- steam turbine power generation
- Steel Authority of India(SAIL)
- Stefan Reichelstein
- stephen chou
- Sterling & Wilson Pvt Ltd
- Sterlite Industries India Ltd.
- Storage
- Storage developers
- Storm
- STPV
- Street Lighting
- strong
- Stuart Wenham
- sub-nanosecond timescale
- Subhash Infraengineers PVt. Ltd
- Subsidy
- subsidy scheme
- such as micro arcs at glued connectors
- Sudhir Power Projects Ltd
- sugar factories
- sugar factory
- Sukhbir Agro Energy Limited
- Sukhbir Singh Badal
- Suman Kumar
- Sun
- SUNBORNE ENERGY RAJASTHAN SOLAR PRIVATE LIMITED
- Suncraft Energy Private Limited
- SunEdison
- Sun Edison
- SunEdison (580 MW)
- Sun Edison Chennai
- Sunedison Energy Holding (Singapore) PTE Ltd
- Sun Edison Energy Holdings Singapore
- Sun Edison Energy Holdings Singapore Pte Limited
- SunEdison Group
- SunEdison Inc.
- Sun Edition-Chennai
- Sun Energy Systems Anand
- Sungandha Power Infrastructure Pvt Ltd
- Sunil Hitech Engineering Ltd
- Sunil Hitech Engineers Ltd.
- Sunil Jain
- Suniva
- sun pharma
- Sun Pharma Medication Private Limited
- SunPower
- Sunrator Technologies LLP
- sunrun
- Sunshell Power
- Sun Source New Delhi
- SunSwitch India Pvt Ltd.
- Suntech
- Suntech Power
- Suntech Power Holdings
- suntech power holdings co
- Sunways
- Sun Yat-sen University
- supplies
- Supply and demand
- Supply chain
- supply constraints
- suppr
- Surana Telecom and Power Limited
- Surana Ventures
- Surat Municipality
- Surcharge
- Sure Energy Systems Private Limited
- Surinder Kumar Negi
- surplus electricity
- SuryaCon 2016 Pune
- Surya Vidyut Ltd
- Su Solartech Systems (P) Ltd
- Sustainability
- Sustainable development
- Sustainable energy
- sustainable energy system
- sustainable food systems
- Sustainable Living
- Sustainable transport
- Sustainable Urban Farms LLC
- Suzlon
- Suzlon (260 MW)
- Svante Arrhenius
- SVTC
- Sweden
- sweet water lake
- Swelect Energy Chennai
- Swelect Energy Systems Ltd
- Sweta Lakra
- Switzerland
- Symphony
- SYMPHONY VYAPAR PRIVATE LIMITED
- Symphony Vyapar Pvt Ltd
- system
- System Quality
- Systems
- Systems Target
- sytem
- T&D
- T-Solar
- Taiwan
- Taiwan and Malaysia
- taking back power
- Talettuytayi Solar Projects One Pvt Ltd
- Tamil Nadu
- Tamil Nadu (Govt. of Tamil Nadu & TNERC)
- tamil nadu electricity board
- Tamil Nadu Electricity Regulatory Commission
- Tamil Nadu Electricity Regulatory Commission (TNERC)
- Tamil Nadu Energy Development Agency
- Tamilnadu Energy Development Agency
- Tamil Nadu Generation and Distribution Company
- Tamil Nadu Generation and Distribution Corporation Limited
- tamil nadu government
- Tamil Nadu Solar
- Tamil Nadu Solar Energy Policy 2012
- Tamil Nadu Solar Policy
- Tamil Nadu Wind Power
- Tamil Nadu Wind Power Banking and Wheeling Charges
- tangedco
- TANGEDCO plea
- target
- target production
- Tariff
- Tariff Hikes
- tariff levels
- tariff policy
- tariff proposal
- Tariff proposals
- Tariff Rate
- tariff reduction
- Tariff regulations
- tariffs
- tariff structure
- Tarun Kapoor
- Tarun Kapoor IAS Joint Secretary
- TASMA
- Tata
- tata bp solar
- Tata Motors
- Tata Power
- Tata Power Bangalore
- Tata Power Community Development Trust
- Tata Power Renewable Energy Limited
- Tata Power Renewables Enrgy Ltd.
- Tata power Solar system Ltd
- Tata Power Solar Systems
- Tata Power Solar Systems Limited
- Tata Power Solar Systems Ltd
- TATA Solar
- Tata Steel Ltd.
- tax
- Taxes
- tax exemption
- tax incentives
- tax relief
- TCoE
- Technical Bids for Solar Power Plants
- technical feasibility
- technological
- technological research laboratories
- technologies
- technology
- Technology roadmap
- Tecpro
- TEDA
- Telangana
- Telangana Solar Policy 2015
- Telangana State Electricity Regulatory Commission
- Telecom Towers
- Temperature
- TERI
- term reliability
- Terms and Conditions
- Terms and conditions for determination of Renewable Energy Tariff
- Terrawatt Initiative
- Tesla
- Tesla Model S
- Tesla Motors
- Tesla Powerwall
- Test definition
- test equipment developers
- testing companies
- TetraSun
- TFO
- Thailand
- Thakaral Service Bangalore
- the Agency for Non-Conventional Energy
- The Cabinet
- The Central Electricity Regulatory Commission
- The Commission
- the Confederation of Indian Industry (CII)
- the Council on Energy
- The Currency Exchange Fund (TCX)
- the Currency Exchange Fund (TCX) and the Terrawatt Initiative (TWI)
- The Hindu
- The Ministry of Environment
- The National
- theoretical efficiency
- The project will reduce New York State electricity-system carbon emissions by up to 5 per.
- Thermal
- thermal energy storage
- thermal power plants
- thermal power plants in india
- Thermal power station
- Thermal Storage
- Thermax Pune
- ThermoPhotovoltaic
- THE SOLAR RESOURCE
- the Tamilnadu Spinning Mills Association
- the United States
- the World Bank Group
- the Renewable Energy Foundation
- Thin film
- thin film modules
- thin film production
- thin film products
- thin films
- Thin film solar cell
- thin film solar cells
- thin film solar panels
- thin film technology
- third generation solar
- Third Party Sale / Captive Use
- Third Party Use
- Thiruvananthapuram
- Thomas F Krauss
- Three-framed Rail System
- Thursday
- Tianjin Yingli New Energy Resources Co Ltd
- Tibet Keguang Industries and Trading Co Ltd
- Tibet Tianwei Yingli New Energy Resources Co Ltd
- Tidal Energy
- Tidal Policy India
- Tidal Power
- Tidal Power Gujarat
- tier 1 suppliers
- tight credit
- Times Group
- Tirumala Tirupati Devasthanam
- Tirunelveli
- titan energy
- TN
- TN Bidding
- TNEB
- TNEDA
- TNERC
- TN industry
- TN Solar Policy 2012
- TN Solar Power Plants
- TN Solar Tender
- TN Wheeling and Banking
- Tobin J. Marks
- Today Green Power Pvt. Ltd.
- Today Homes- New Delhi
- TOE
- Tokelau
- Tokyo Electric Power Company
- Tonk Rajasthan
- Top 5 predictions for solar pv
- Top 10 companies
- Top Gear
- Top Solar Manufacturers
- TopSun Energy
- Top Sun Gandhinagar
- Tornado
- Torrent
- Torrent Power
- Torrent Power Limited Ahmedabad
- Torrent Power Limited Surat
- Toshiba
- Total commissioned capacity till 31-01-16 (MW)
- Total Financial Outlay
- Total MNRE
- tourbo
- Toyota
- Toyota Prius
- TPC
- TPDDL
- trade dispute
- trade investigations
- Trading
- traffic cops
- traffic signals
- Tranche-I
- Tranche-II
- Tranche-III
- Trancik
- Transformation
- Transformers Industrial Electronics
- transitions
- Transmission
- Transmission and Distribution charges for wheeling of power
- Transmission and distribution losses
- Transmission line
- transmission service agreement
- Transmission System
- transparent electrode
- transportation
- Tree
- Trees
- Trina
- Trina Solar
- Trina Solar (Changzhou) Science &
- Trina Solar (Changzou) Science and Technology
- Triple junction
- triplet exciton
- Tripura
- TSERC
- TSNPDCL
- TSSPDCL
- TSSPDCL/01/LTSPP/2015
- TSTRANSCO
- Tuk Tuk
- Turbines
- Turkey
- turnkey project
- Tyagi
- Türkiye
- U-Solar Clean Energy Solutions Pvt. Ltd.
- U.N. Intergovernmental Panel on Climate Change
- U.S. Securities and Exchange Commission
- UBS
- UCLA
- UC Riverside
- UERC
- Ujaas Energy Ltd
- UK
- Ukraine
- Ultimate Sun Systems Pvt. Ltd.
- Ultratech Cement Ltd.
- Ultra Thin Solar Cell
- Uma Shankar
- Uneecops Technologies Ltd
- Unethical
- UNFCCC
- uniform tariff
- union member states
- union power ministry
- Union Territories
- Union Territory
- United Arab Emirates
- United Nations Department of Economic and Social Affairs (UNDESA)
- United Phosphorus
- united states
- United States Congress
- United States Court of International Trade
- United States Department of Commerce
- United States Department of Energy
- United States dollar
- United States Environmental Protection Agency
- United Telecoms Limited
- United Telecoms Ltd
- Unit price
- units of electricity
- Universities of York
- University of California
- university of california berkeley
- University of California Los Angeles
- University of California Riverside
- University of Cincinnati
- University of Georgia
- University of Illinois at Urbana–Champaign
- University of Wisconsin–Madison
- University of York
- Unpaid Bills
- unprecedented prosperity
- Unprofessional
- Untrustworthy
- UP
- UPCL
- UPERC
- UP India
- UPNEDA
- UP Net Metering
- UPPCL
- upper assam
- UPSIDC
- UP Solar PV RFP
- Uratom Solar (India) Private Limited
- Urban Dev. Trust Pvt. Ltd.- Ratlam
- UREDA
- US
- USA
- u s a
- usage of water
- USAID
- Us Commerce Department
- us court of international trade
- US Customs and Border Protection
- Us Exim Bank
- US sends first commercial offshore wind power to its grid
- UT
- Utilities
- utility
- utility electricity prices
- Utility Scale Power Plant Design
- Uttarakhand
- Uttarakhand (Govt. of Uttarakhand & UERC)
- UTTARAKHAND ELECTRICITY REGULATORY COMMISSION
- Uttarakhand Power Corporation Ltd
- Uttar Gujarat Vij Co. Ltd
- Uttar Pra
- Uttar Pradesh
- Uttar Pradesh (Govt. of Uttar Pradesh)
- Uttar Pradesh New and Renewable Energy Development Agency
- Uttar Pradesh Power Corporation Ltd.
- Uttar Pradesh Power Corporation Ltd. (UPPCL)
- Uttar Pradesh Renewable Energy Commission (UPERC)
- Uttar Pradesh Solar Policy
- Uttar Pradesh State Industrial Corporation
- UV fluorescence
- uv radiation
- Uzbekistan
- V.S. Achuthanandan
- vacuum deposition
- Vahan Garboushian
- Van der
- Variable Cost
- VAT
- VBC Renewable Energy Pvt Ltd
- Vedanta Ltd.
- vedanta resources plc
- Veddis Solar Hyderabad
- vegetable
- Vehicles
- Velhe Taluka
- Vellore
- venture capital
- Vestas
- VGF
- VGF Securitization Agreement
- Viability Gap Funding
- vibrant gujarat
- Vice President[Assets]
- Victoria Memorial
- Vidyut Vyapar Nigam
- Vietnam
- vikas nigam
- Vikram
- Vikram Solar
- Vikram Solar Kolkata
- Vikram Solar Pvt Ltd New Delhi
- village electrification
- Village Lighting
- villages in pakistan
- Vineet Jain
- Vintage Multiplier
- Visakhapatnam
- Visa Steel Ltd.
- Vishva Vishal Eng Ltd
- Vishwaj Energy Pvt. Ltd
- visual inspection
- Vivek Chaturvedi
- Vizianagaram
- VOC
- VolksWagon
- Volt
- Voltage
- V P Raja
- VR Patil Vividh Vidyuth Nirman Pvt. Ltd.
- V Saibaba
- VW
- Vyomaa Energy Private Limited
- Vénissieux
- Waaree
- Waaree Energies Ltd Mumbai
- Waaree Energy
- Waaree Group
- Waa Solar Private Limited- Tumkur 1
- Waa Solar Private Limited- Tumkur 2
- WAA Solar Pvt. Limited
- Waa Solar Pvt. Ltd.
- Wacker
- Wage
- Wall Street Journal
- Waneep Solar Pvt Ltd
- Wardha Power Company Ltd.
- Waree Energies
- Waree Energies Ltd.
- Waree energy Mumbai
- Warehouses
- Warranty Issues
- Washington State University Tri-Cities
- Waste
- waste incineration
- waste management
- Waste to Energy
- Waste to Power
- Water
- water contamination
- Water heating
- water heating systems
- Water mills/micro hydel
- waterproof
- Watt
- Watt-peak
- Wave
- Weather
- Weather forecasting
- weather parameters
- weather satellite data
- weather variables
- Web portal
- websol
- Websol Energy Systems
- Websol Energy Systems Limited
- Websol Energy Systems Ltd.
- Wednesday
- Welspun
- Welspun Energy
- Welspun Group
- Welspun Renewable
- Welspun Renewable - Mumbai
- Welspun Renewables Energy Ltd.
- Welspun Renewables Energy Pvt. Ltd.. Noida
- Welspun Renewables Energy Pvt Ltd
- Welspun Renewables Pvt Ltd
- WELSPUN SOLAR AP PRIVATE LIMITED
- Welspun Solar Kannada Private Ltd.
- west bengal
- West Bengal (Govt. of West Bengal & WBERC)
- Western Ghats
- west godavari
- West Singbhum district in Jharkhand
- West Virginia
- wheeling
- Wheeling and Banking
- Wheeling Charges of Distribution business
- Wheeling Tariff
- william gibson
- William Shockley
- Wind
- Wind-calming
- Wind Association
- wind auction
- Wind Banking
- Wind based power plants
- wind blog
- Wind blog india
- wind cartel
- Wind Charter
- wind components
- Wind Data
- Wind Energy
- Wind Energy Power Projects
- wind energy projects
- wind energy technology
- Windfall gain
- windfall gains
- windfall profits
- wind farm
- WInd Farms
- wind grid
- Wind India
- Wind India Blog
- wind industry
- Winding Wires
- Wind IPP
- Wind Load on PV
- Wind Loan
- Windmills
- wind plants
- Wind Policy
- Wind Power
- Wind Power Banking
- wind power generation
- wind power generator
- wind power generators
- Wind Power India
- wind power plants
- wind power producers
- wind power produces
- Wind Power Project
- wind power projects
- Wind Producers
- Wind Project
- Wind Projects
- wind rec
- Wind Renewable Energy
- wind software
- wind solicitation
- Wind Speeds
- Wind turbine
- wind turbine manufacturers
- Wind Turbines
- wind turbines cost
- Wind Wheeling and Banking
- Winfried Kretschmann
- wire cables
- Wire Management
- with grid
- Women
- working committee
- World Bank
- World Bank Group
- World energy consumption
- World energy outlook 2030
- world energy supply
- Worlds Largest Solar Park
- World Trade Centre
- world trade organisation wto
- World Trade Organization
- World Trade Organization (WTO)
- World Wide Fund For Nature
- worldwide glut
- WRETC
- WTG
- WTO
- wto commitments
- Wuxi Sun-Shine Power
- Wuxi Suntech Power
- WWF
- Xinjiang Yingli New Energy Resources Co Ltd
- XL Energy Ltd.
- Xpanz Energy Solutions Llp
- Yarrow Infrasturcture Ltd
- Yashraj Khaitan
- Yingi Energy (China)
- Yingli
- Yingli Energy (Beijing) Co Ltd
- Yingli Energy (China)
- Yingli Green
- yingli green energy
- Yingli Green Energy Holding Company Limited
- Yingli Green Energy Hong Kong Trading Limited
- Zachary Favors
- Zandu Realty Ltd.
- Zealand
- zero-carbon
- zero carbon emissions
- Zero Investment Model
- Zeus Solar Epc Pvt. Ltd.
- Zhejiang Jinko Solar
- Zhenjiang Ren De New Energy Science Technology
- Zhenjiang Rietech New Energy Science Technology
- Zinc–air battery
- Zivah International Private Limited
- Zodiac Energy Ahmadabad
- Zodiac Energy Pvt. Ltd.
- `M/s. D.S. Education Ventures Pvt. Ltd.. Haridwar
- · Project Developers
- โซล่าร์ PV
- โซล่าร์ประเทศไทย
- โซล่าร์รูฟท็อป
- โซล่าเซลล์
- ₹/kWh
- ₹3.93
Blog Followers


